

Strategic allocation to Asia fixed income
Global markets currently face high levels of uncertainty. Inflation remains elevated in developed economies, the trajectory of monetary policy is unclear, and complex geopolitical tensions add further complexity to the outlook. In times like this, it makes sense for fixed income investors to broaden their portfolio exposure.
Asian fixed income presents attractive opportunities to diversify across markets, supported by solid macroeconomic fundamentals, accelerating AI development, ongoing supply chain realignment, and relatively compelling yields. Its strength compared to other regions makes a strong case for investors to consider a strategic allocation to Asia in their global portfolios.
Navigating global challenges
It is a challenging time for the global economy. Not only are there serious disruptions to trade, but there are also growing concerns about the high levels of indebtedness in some of the largest economies. But despite the difficult backdrop, Asia remains an economic bright spot, accounting for around 60 per cent of global growth1, while at the same time presenting relatively benign levels of inflation compared to western economies.
Asia is not homogeneous. Each market presents its own growth story, monetary policy trajectory, and credit profile, creating a diverse opportunity set for strategic and tactical allocations that can potentially result in a more resilient portfolio.
Hong Kong dollar (HKD) bonds complement a broader Asia allocation. For investors with HKD liabilities, the market provides high-quality assets in the currency of the obligation. For USD-based investors, Hong Kong’s currency link to the US dollar can also help limit currency risk.
Issuers in the Hong Kong dollar market typically have good credit quality, including the Hong Kong SAR government, as well as other well-rated quasi-sovereign, supranational and corporate issuers. Yields in Hong Kong are relatively modest, but the market’s robust credit fundamentals and relatively contained local inflation have supported its defensive characteristics. This can make HKD bonds a comparatively stable source of defensive exposure.
For some investors, accessing the market through individual securities can be challenging. Institutional minimum sizes put many issues out of reach, liquidity can be thin in some parts of the market, and most HKD non-government bonds are issued through private placements rather than via public offering. For that reason, many investors find a fund or ETF the more practical route into the asset class.
Asia USD credit: resilience amid volatility
Beyond local currency markets, the Asia US dollar bond market can provide diversification benefits for global investors, underpinned by robust investment grade fundamentals and improving high yield conditions. Asia dollar investment grade credit has historically held up well in periods when external events have widened spreads – such as the COVID-19 pandemic, the start of the conflict in Ukraine in 2022, the US implementation of new tariffs in 2025, and the energy price shock that followed the blocking of the Strait of Hormuz.
Resilience, in part, reflects the quality and composition of the Asia credit universe. About 87 per cent of the constituents in the J.P. Morgan Asia Credit Index (JACI) is classified as investment grade2. Furthermore, the index’s composition has become less concentrated over time with greater diversification across geographies and sectors.
Within Asia credit, two investment themes, in particular, stand out.
The first is supply chain realignment. International companies are implementing so-called “China plus one” strategies, which extend supply chains to other Asian economies. At the same time, more Chinese companies are expanding manufacturing operations across the region, especially in Southeast Asia. All this drives capex and local infrastructure financing, which may support a broader regional corporate bond universe – potentially giving investors greater diversification and more opportunities to identify relative value across markets and sectors.
The second theme is artificial intelligence. Select Asian technology companies are likely to see demand lift as AI adoption widens. Momentum remains strong in Asian hardware tech, such as leading regional foundry and memory chip companies, which stand to benefit from data centre demand and a memory super upcycle. Fundamentals in these segments remain stable, with manageable capex well within financial limits.
Often thought of as an equity story, AI is increasingly relevant to Asian fixed income as well, broadening the investable universe. Technology now accounts for about 10 per cent of the Asia USD investment grade universe, underscoring the rapid growth of tech- and AI-linked exposure.3
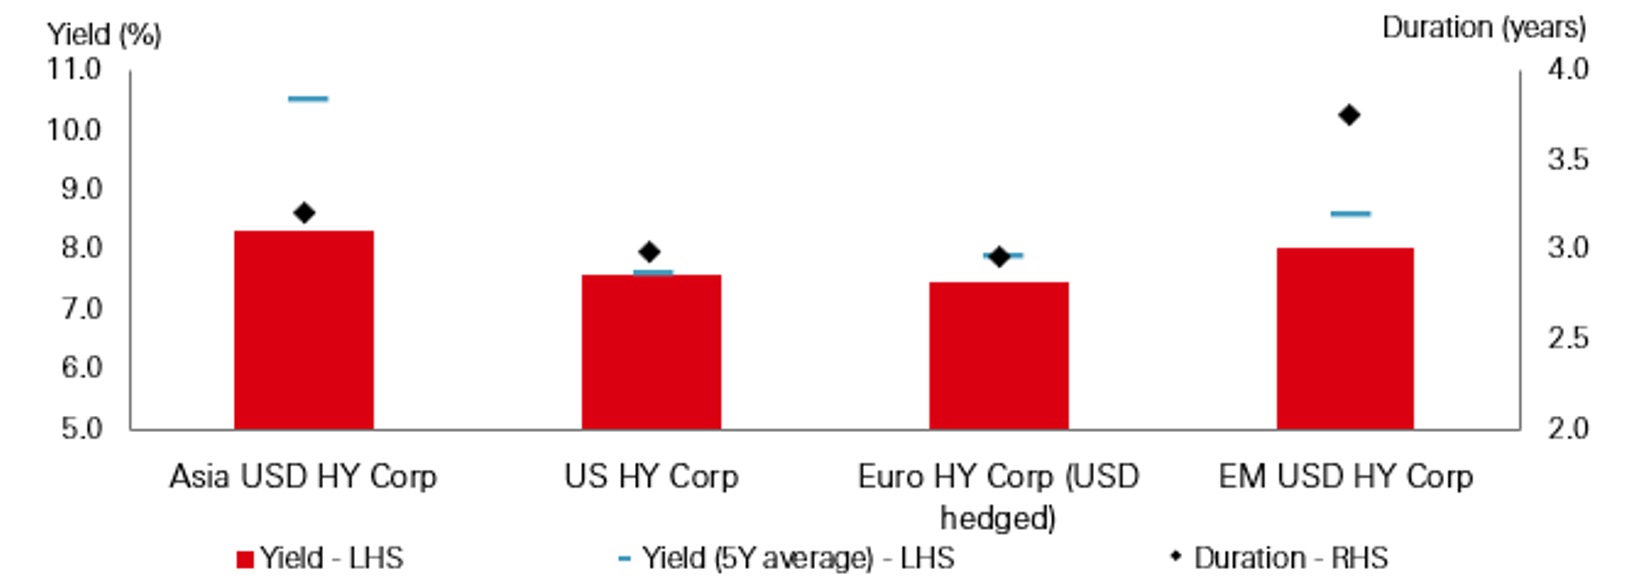
Spreads in both investment grade and high yield markets have narrowed in recent years, with high yield making a recovery after China’s property market downturn.
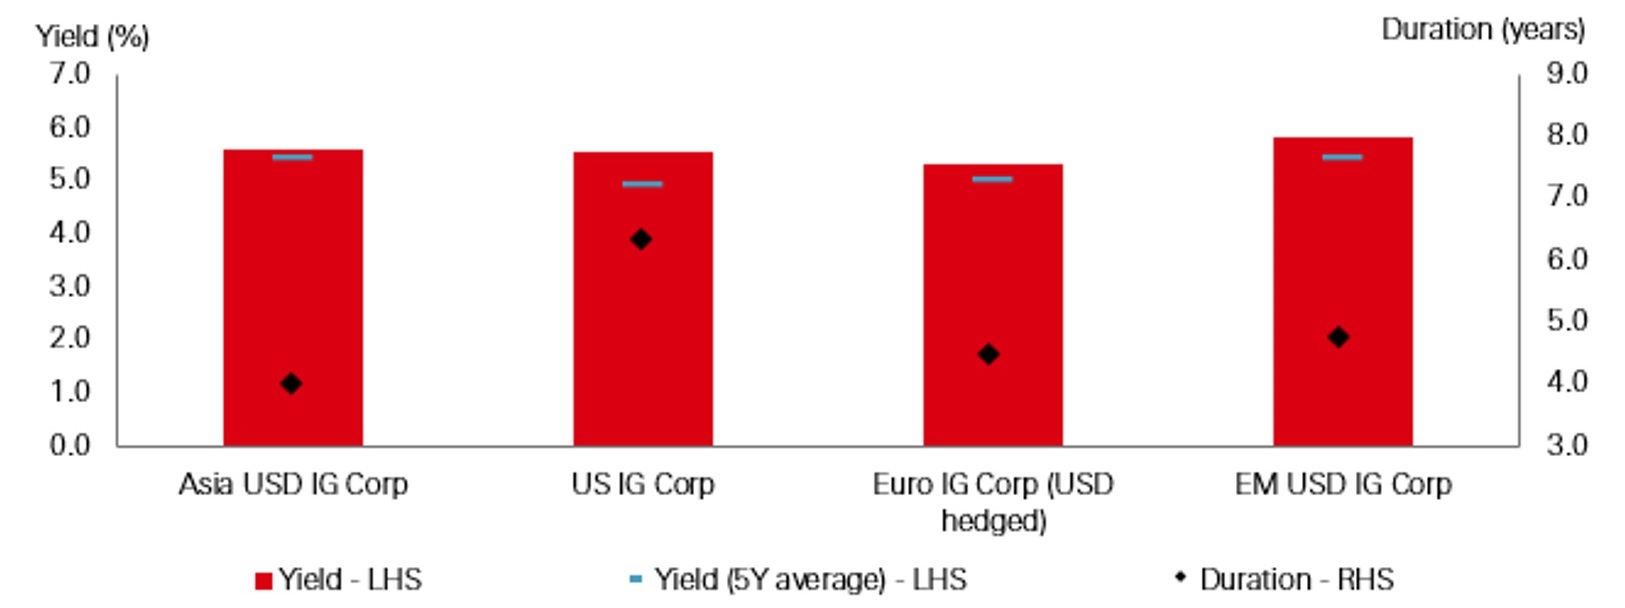
Although spreads are relatively tight, Asia credit continues to be supported by shorter duration, robust local funding markets and sound corporate fundamentals. Potential alpha can be found in relative value opportunities and careful security selection.
Fig. 1 Asia USD bonds trade at compelling valuations; shorter duration vs other markets
IG corporate yield comparison
Click the image to enlarge
HY corporate yield comparison
Click the image to enlarge
Note 1: Euro IG Corp and Euro HY Corp Yields listed are USD hedged. Indices used: US IG Corp — ICE BofA US Corporate Index; US HY Corporate — ICE BofA US High Yield Index; Euro IG Corporate — ICE BofA Euro COrporate Index; Euro HY Corp — ICE BofA Euro High Yeild Index; Asia IG Corp — JP Morgan Asia Credit Corporate Index Investment Corporate Emerging Markets Bond Broad Diversified Index High Grade; EM HY Corp — JP Morgan Corporate Emerging Markets Bond Broad Diversified Index High Yield
Source: JP MOrgan, BAML, as of 31 August 2026.
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. The information provided is for illustrative purpose only.
Building a strategic allocation
In short, all these factors make a case for treating Asian fixed income as a strategic allocation rather than a tactical one. The region’s growth profile, subdued inflation, and a diverse mix of markets gives investors more ways to build resilience into a global portfolio, while supply chain realignment and AI adoption are opening up parts of the corporate universe that were previously the reserve of equity investors.
Within that allocation, HKD bonds serve a more specific purpose, acting a defensive, high-rated local-currency holding for investors with HKD liabilities, and a way for USD-based investors to add regional exposure without taking in significant currency risk.
Diversification does not ensure a profit or protect against loss. The views expressed above were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. This information should not be construed as a recommendation to invest in the specific country, product, strategy or sector.
Find out more about the Hong Kong dollar bonds: ABF Hong Kong Dollar Bond Index Fund
1. IMF, October 2025
2. Source: JP Morgan Asia Credit Index (JACI) as of 31 July 2026.
3. HSBC Asset Management, April 2026
Important information
For professional investors and intermediaries only. This document should not be distributed to or relied upon by retail clients/investors.
This document provides a high level overview of the recent economic environment. It is for marketing purposes and does not constitute investment research, investment advice nor a recommendation to any reader of this content to buy or sell investments. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination
This document is prepared for general information purposes only and does not have any regard to the specific investment objectives, financial situation and the particular needs of any specific person who may receive it. Any views and opinions expressed are subject to change without notice. This document does not constitute an offering document and should not be construed as a recommendation, an offer to sell or the solicitation of an offer to purchase or subscribe to any investment. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Global Asset Management (Hong Kong) Limited (“AMHK”) accepts no liability for any failure to meet such forecast, projection or target. AMHK has based this document on information obtained from sources it reasonably believes to be reliable. However, AMHK does not warrant, guarantee or represent, expressly or by implication, the accuracy, validity or completeness of such information. Investment involves risk. Past performance is not indicative of future performance. Please refer to the offering document for further details including the risk factors. This document has not been reviewed by the Securities and Futures Commission. Copyright © HSBC Global Asset Management (Hong Kong) Limited 2026. All rights reserved. This document is issued by HSBC Global Asset Management (Hong Kong) Limited.
Content ID: D077608; Expiry Date: 30.09.2027