

Investment Monthly
Key Takeaways:
House View
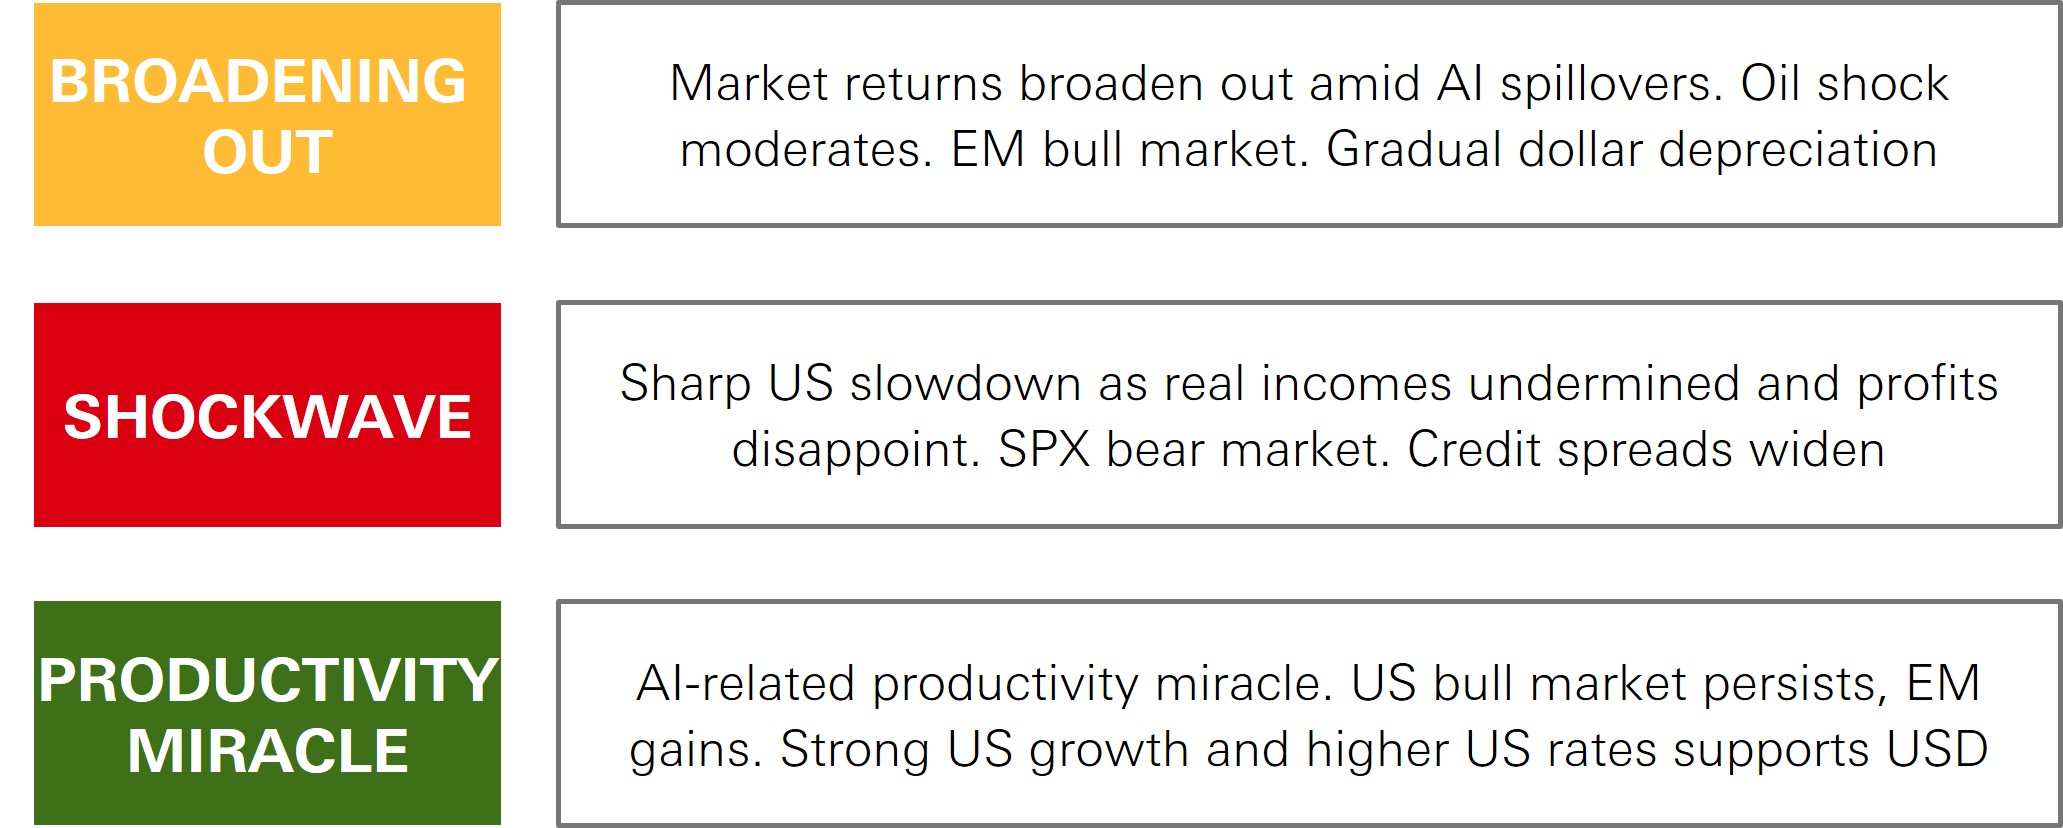
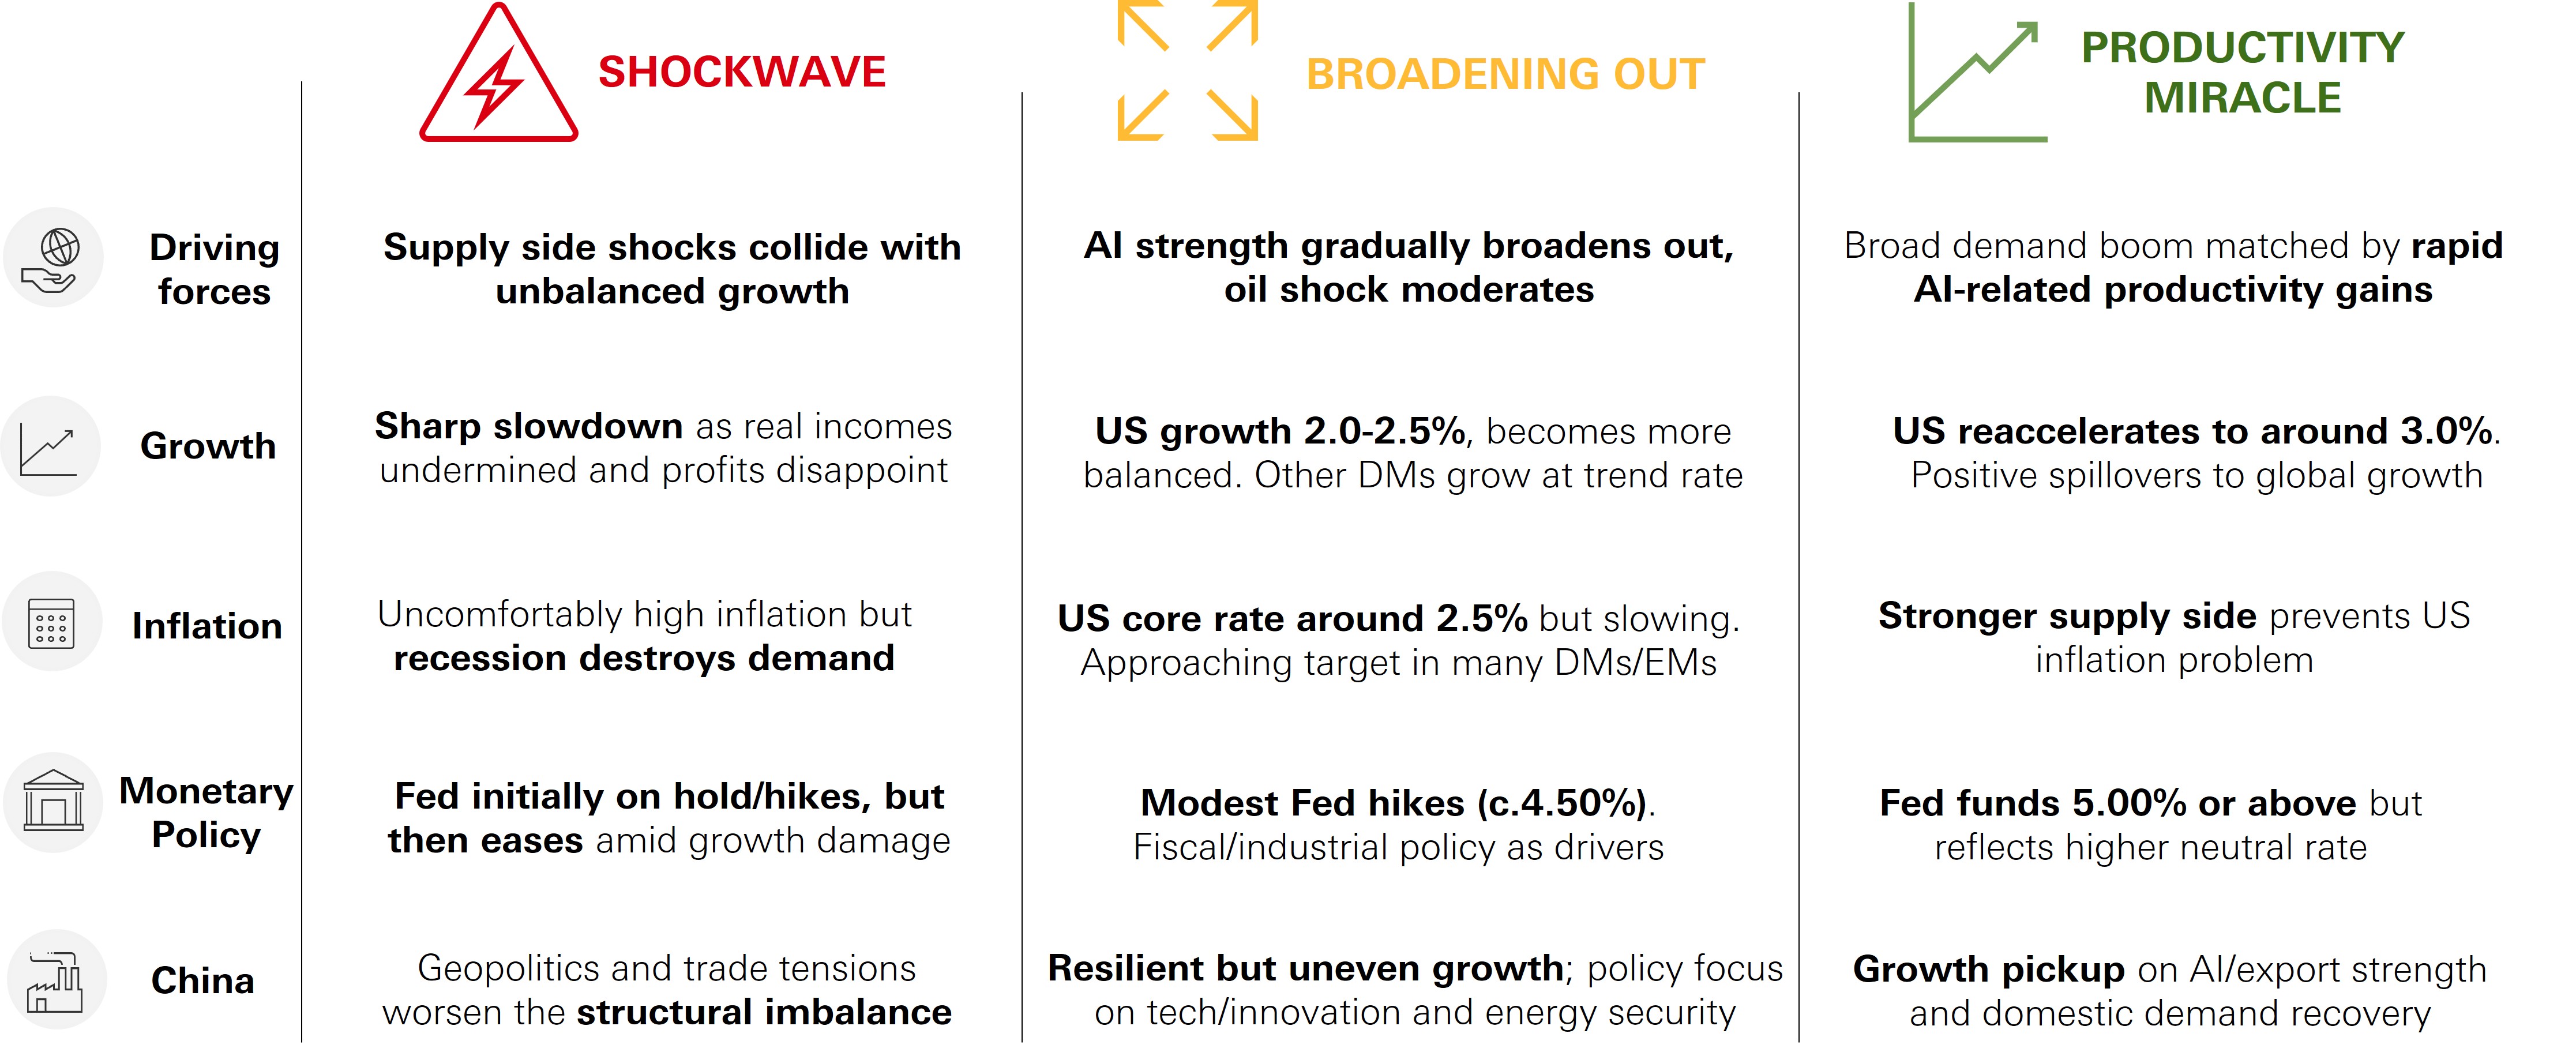
- Our central scenario remains a “broadening out” of profits and market performance, helped by AI spillover effects. Markets should remain resilient, but sticky inflation, higher real yields, and geopolitical risks could cause volatility
- Equities are supported by strong earnings, but stretched valuations, and concentrated AI exposure leave little room for disappointment. As the AI capex boom matures, upstream and downstream sectors should benefit
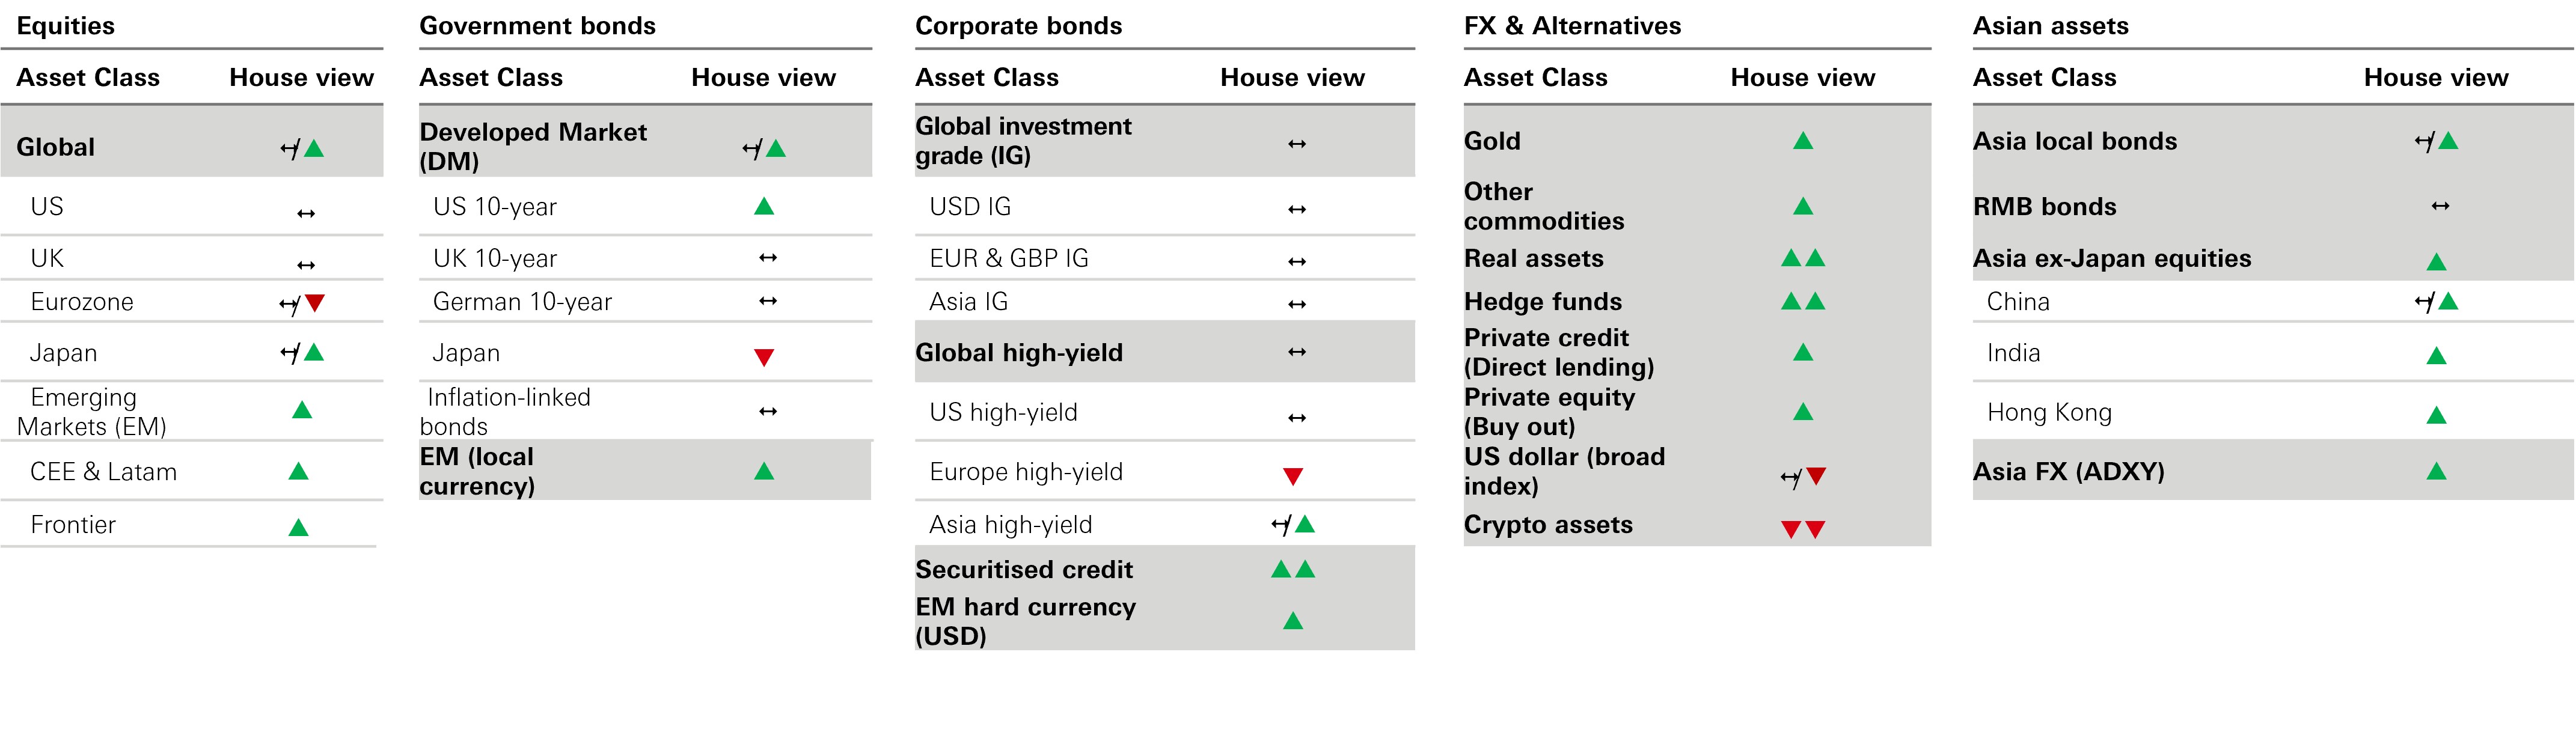
- We see strength in Japan, emerging markets and selected European equities, alongside high-quality investment-grade credit and EM fixed income. Elevated DM government bond yields can provide income for portfolios. In periods of market stress, bonds’ hedging characteristics should also re-emerge
Macro Outlook
- Continued Middle East tensions have boosted oil and refined product prices. Elevated energy prices have raised concerns about upside inflation risks and contributed to a rise in bond yields across many economies
- US domestic demand is solid but imbalanced. However, strong profits should support a broadening out of investment beyond AI, improved labour market conditions, and a gradual rebalancing of the K-shaped dynamics
- AI and policy buffers have supported Asia’s growth, but it is exposed to the risk of global AI demand shifts and energy supply shocks. China’s growth is resilient amid technology and export strength, but still imbalanced
Policy Outlook
- Policy uncertainty is high. Central banks are facing difficult growth-inflation trade-offs due to supply-side shocks. Fiscal and industrial policy is more activist, but elevated government debt is a constraint
- The Federal Reserve hiked by 25bp with the projections suggesting 1-2 more increases in this cycle. Recent ECB comments suggest further tightening, but the rate path is dependent on energy prices. The BoE signalled a near-term rate hike
- The interplay of energy headwinds, tech tailwinds, and fiscal support has driven a hawkish monetary policy tilt across Asia amid higher global rates. China’s policy balances short-term macro stability with longer-term structural priorities
Scenarios
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. Diversification does not ensure a profit or protect against loss. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security.
Source: HSBC Asset Management as at October 2026.
House View
Market leadership should broaden out as the AI boom matures, but sticky inflation, higher real yields and geopolitical uncertainty could cause volatility. Stocks are supported by strong profits, but stretched valuations and concentrated AI exposure are risks. Value plays – including emerging market stocks and fixed income – can provide portfolio diversification
- Equities – Global stock markets are being supported by strong earnings momentum, but valuations – particularly in the US – leave little room for error. High valuations, AI concentration, and geopolitical risks could cause episodic volatility
- Government bonds – A higher-for-longer rates regime offers an opportunity to generate income from DM bonds. If inflation stays anchored, bonds could re-emerge as an effective hedge in periods of macro weakness or equity market stress
- Corporate bonds – Investment grade spreads are tight, but attractive all-in yields and healthy balance sheets are supportive. Selectivity is key given that surging issuance by AI hyperscalers risks magnifying tech exposure in multi-asset portfolios
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. You cannot invest directly in an index. The level of yield is not guaranteed and may rise or fall in the future. House view represents a >12-month investment view across major asset classes in our portfolios. Source: HSBC Asset Management as at October 2026.
Asset class performance at a glance
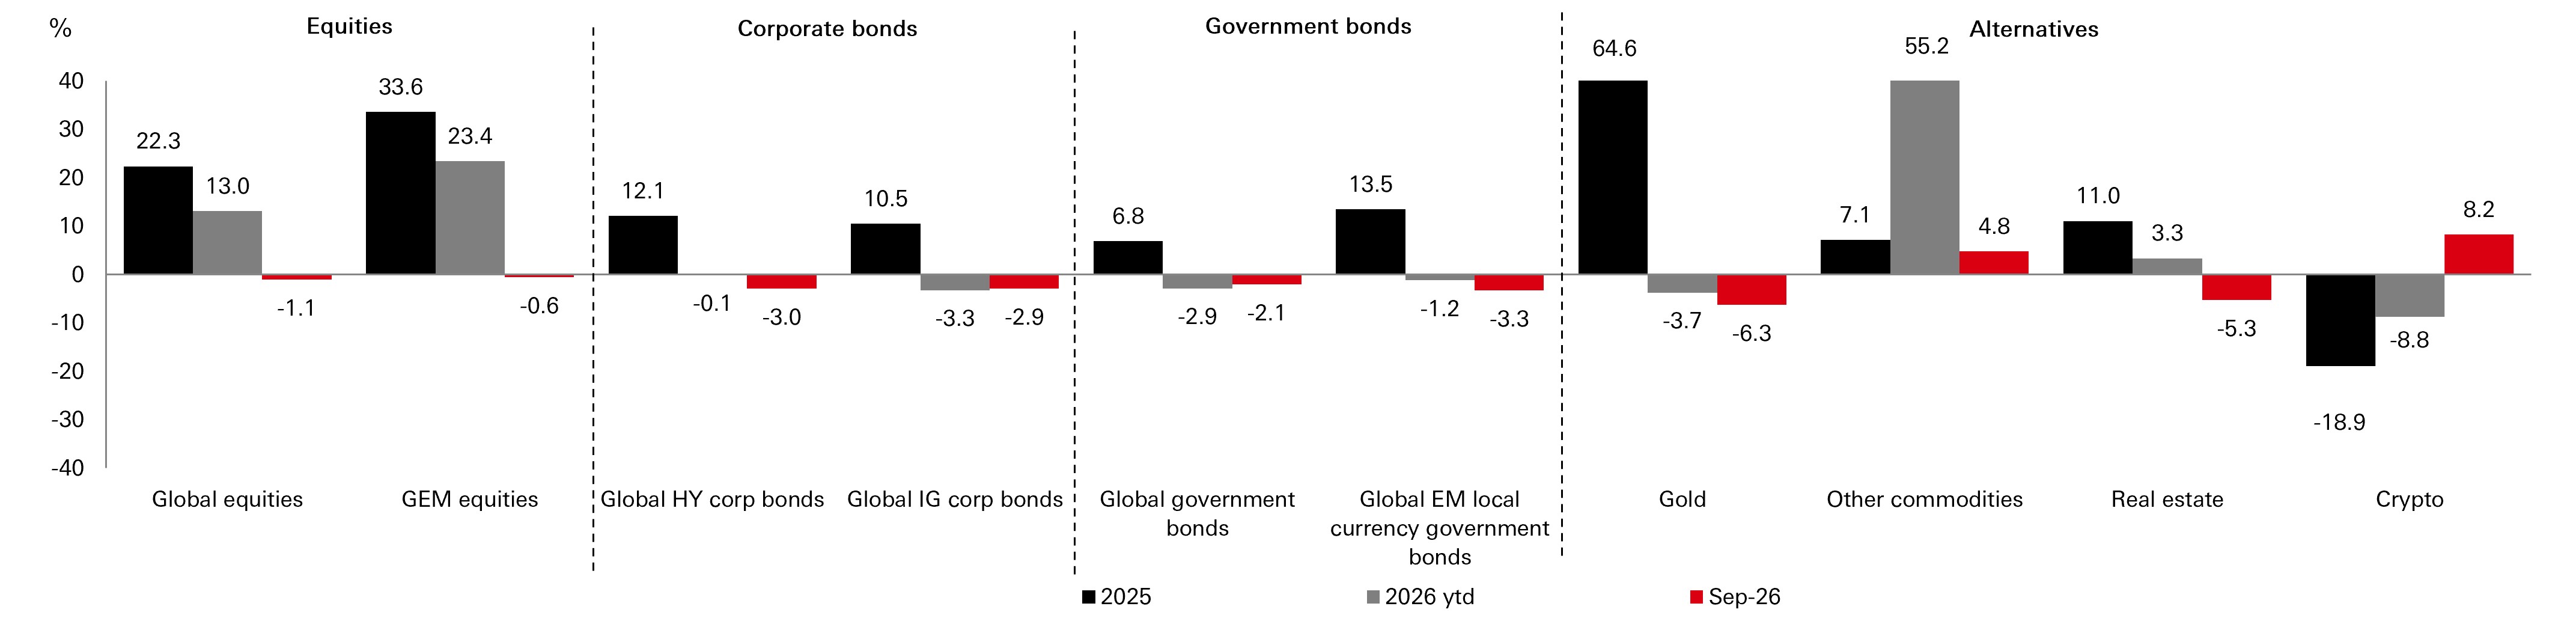
Developed market government bonds sold-off sharply in September as markets priced higher-for-longer rates, fiscal concerns, and robust growth. Global equities declined, but tech stocks were resilient given their strong earnings outlook and the AI investment boom. Alternatives were mixed, with oil and crypto strong but gold and listed real assets weak
- Government bonds – Sovereign bonds fell (yields rose sharply) in response to sticky inflation and a higher-for-longer rates outlook, fiscal concerns, and competition for flows amid heavy credit issuance by AI hyperscalers
- Equities – Global equities saw modest declines, but the AI boom provided some resilience, with technology-led markets still strong. Japan and Latin American indices also managed to deliver positive returns. China and India remained subdued
- Alternatives – Rising bond yields and a stronger US dollar contributed to a slump in the gold price during the month. Oil prices remained elevated and crypto assets saw further gains, while infrastructure and real estate indices declined
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. The views expressed above were held at the time of preparation and are subject to change without notice. The level of yield is not guaranteed and may rise or fall in the future. Source: Bloomberg, all data above as at close of business 30 September 2026 in USD, total return, month-to-date terms. Note: Asset class performance is represented by different indices. Global Equities: MSCI ACWI Net Total Return USD Index. Global Emerging Market Equities: MSCI Emerging Market Net Total Return USD Index. Corporate Bonds: Bloomberg Barclays Global HY Total Return Index value unhedged. Bloomberg Barclays Global IG Total Return Index unhedged. Government bonds: Bloomberg Barclays Global Aggregate Treasuries Total Return Index. JP Morgan EMBI Global Total Return local currency. Commodities and real estate: Gold Spot USD/OZ, Other commodities: S&P GSCI Total Return CME. Real Estate: FTSE EPRA/NAREIT Global Index TR USD. Crypto: Bloomberg Galaxy Crypto Index. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index.
Macro scenarios
Click image to enlarge
Market scenarios
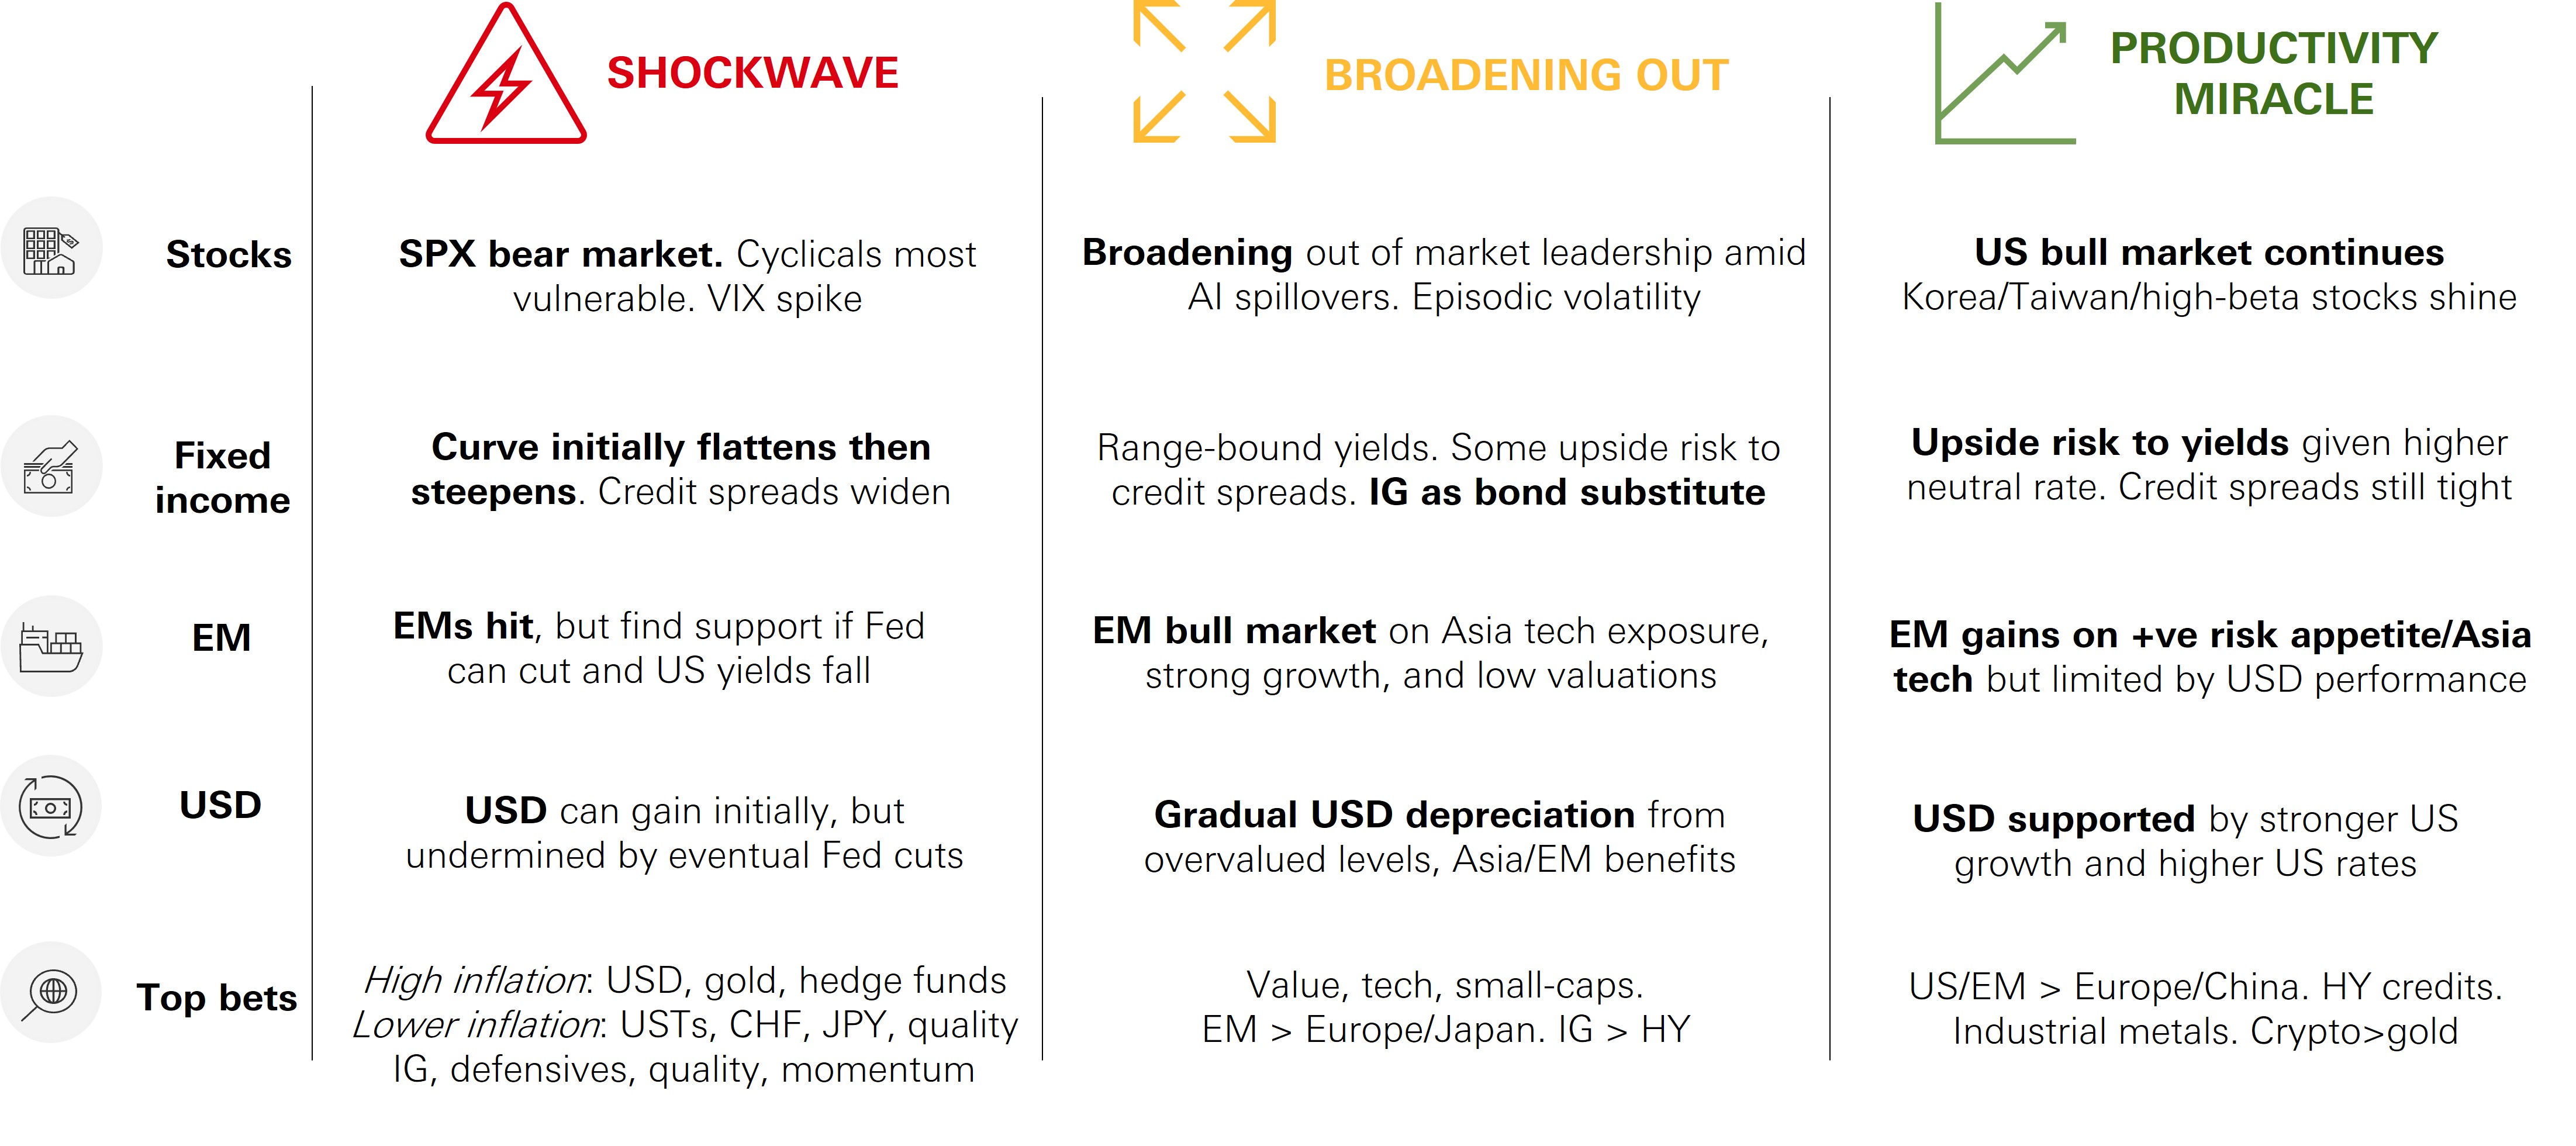
Click image to enlarge
Economic outlook
Managing inflation risks
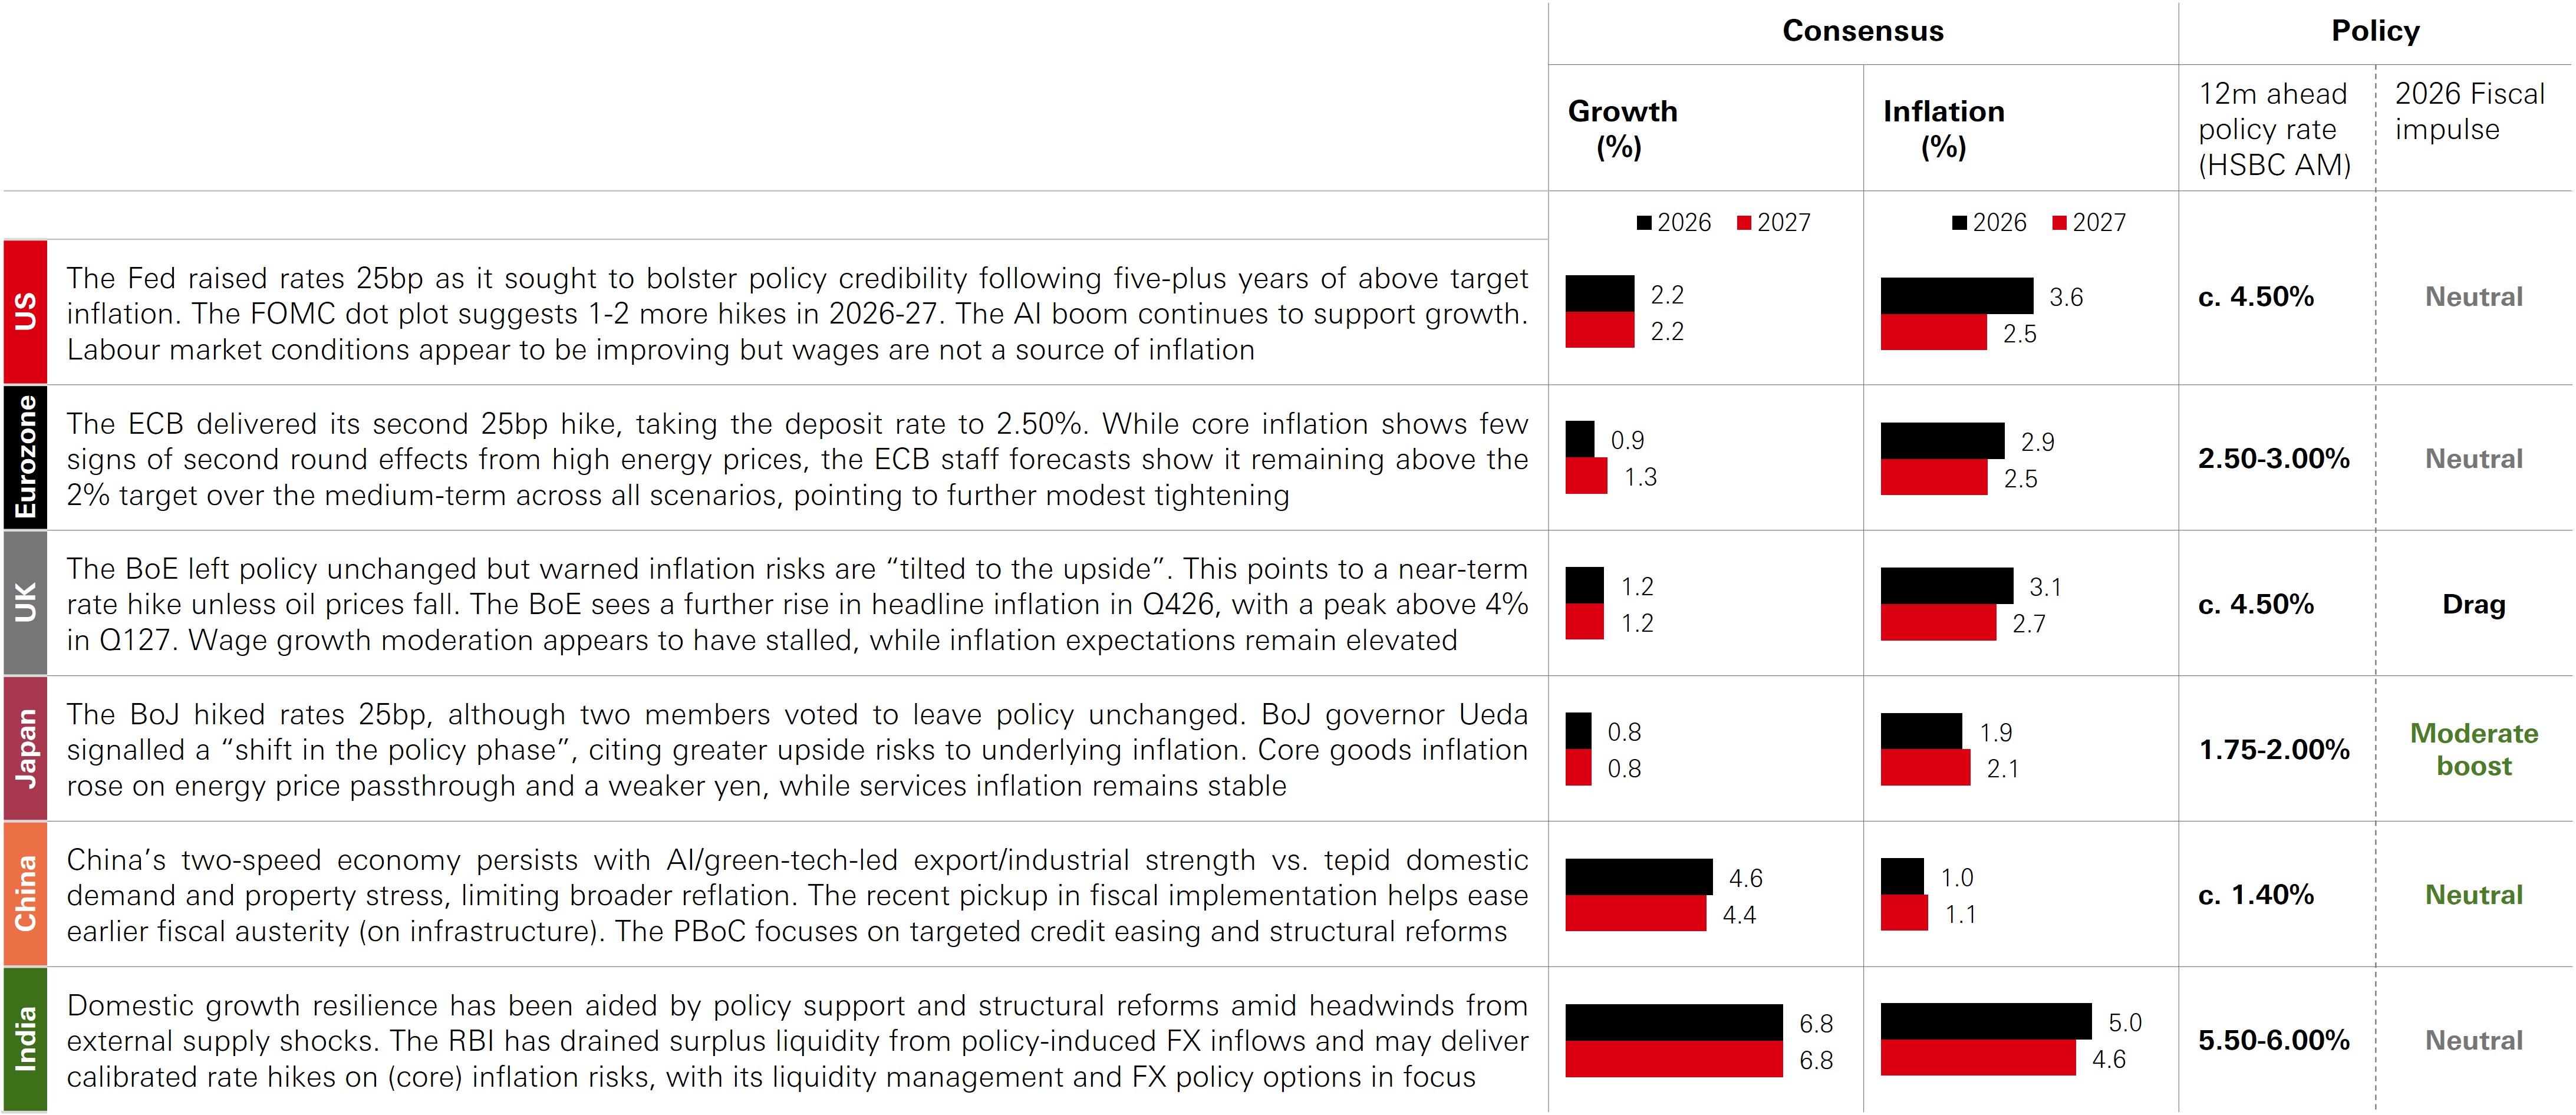
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security.
Source: HSBC Asset Management, consensus numbers from Bloomberg, October 2026.
Events calendar: H2 2026
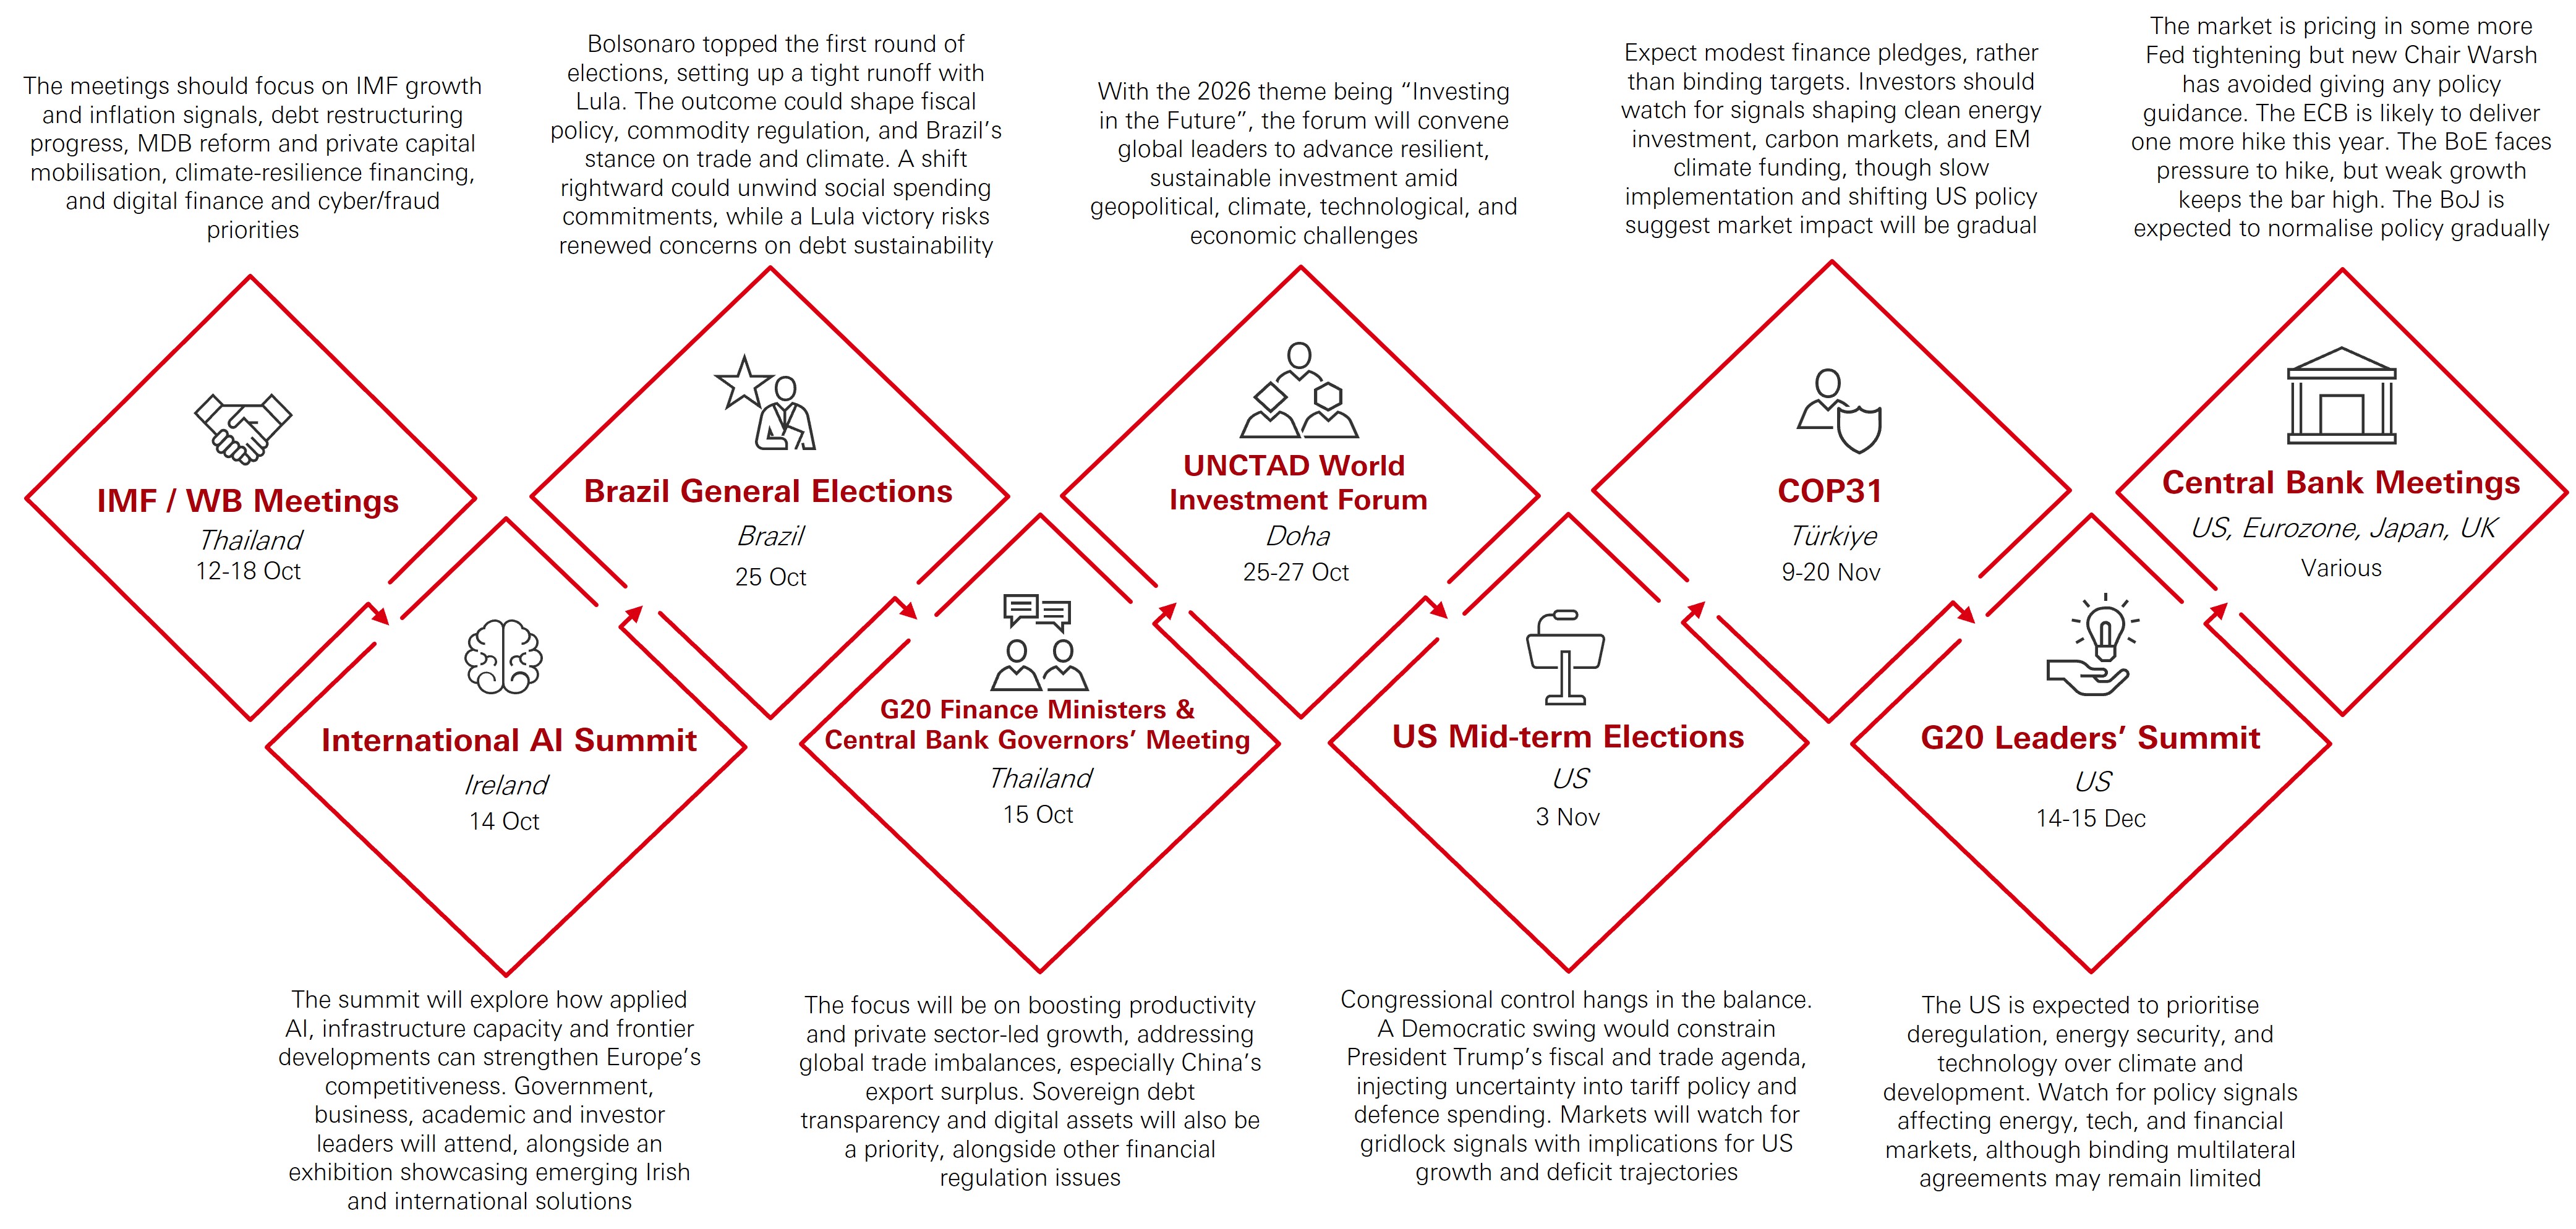
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. The views expressed above were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security.
Source: HSBC Asset Management, October 2026.
Investment Views
Asset class positioning
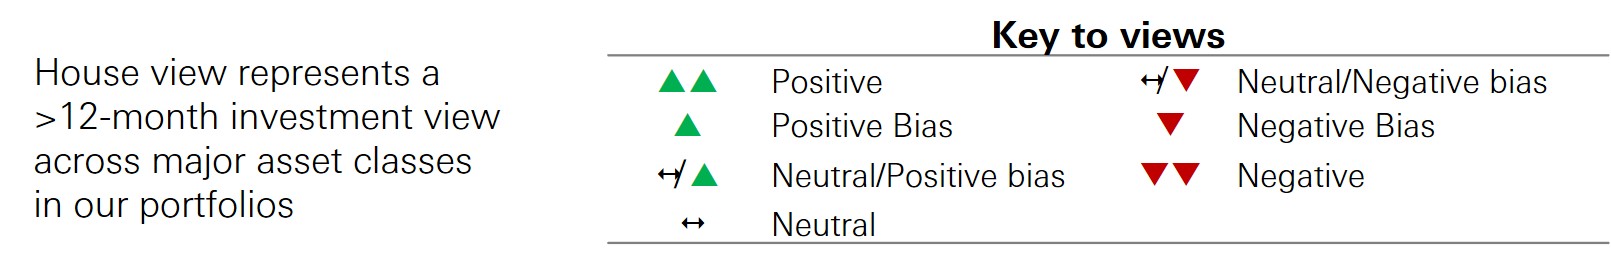
Click image to enlarge
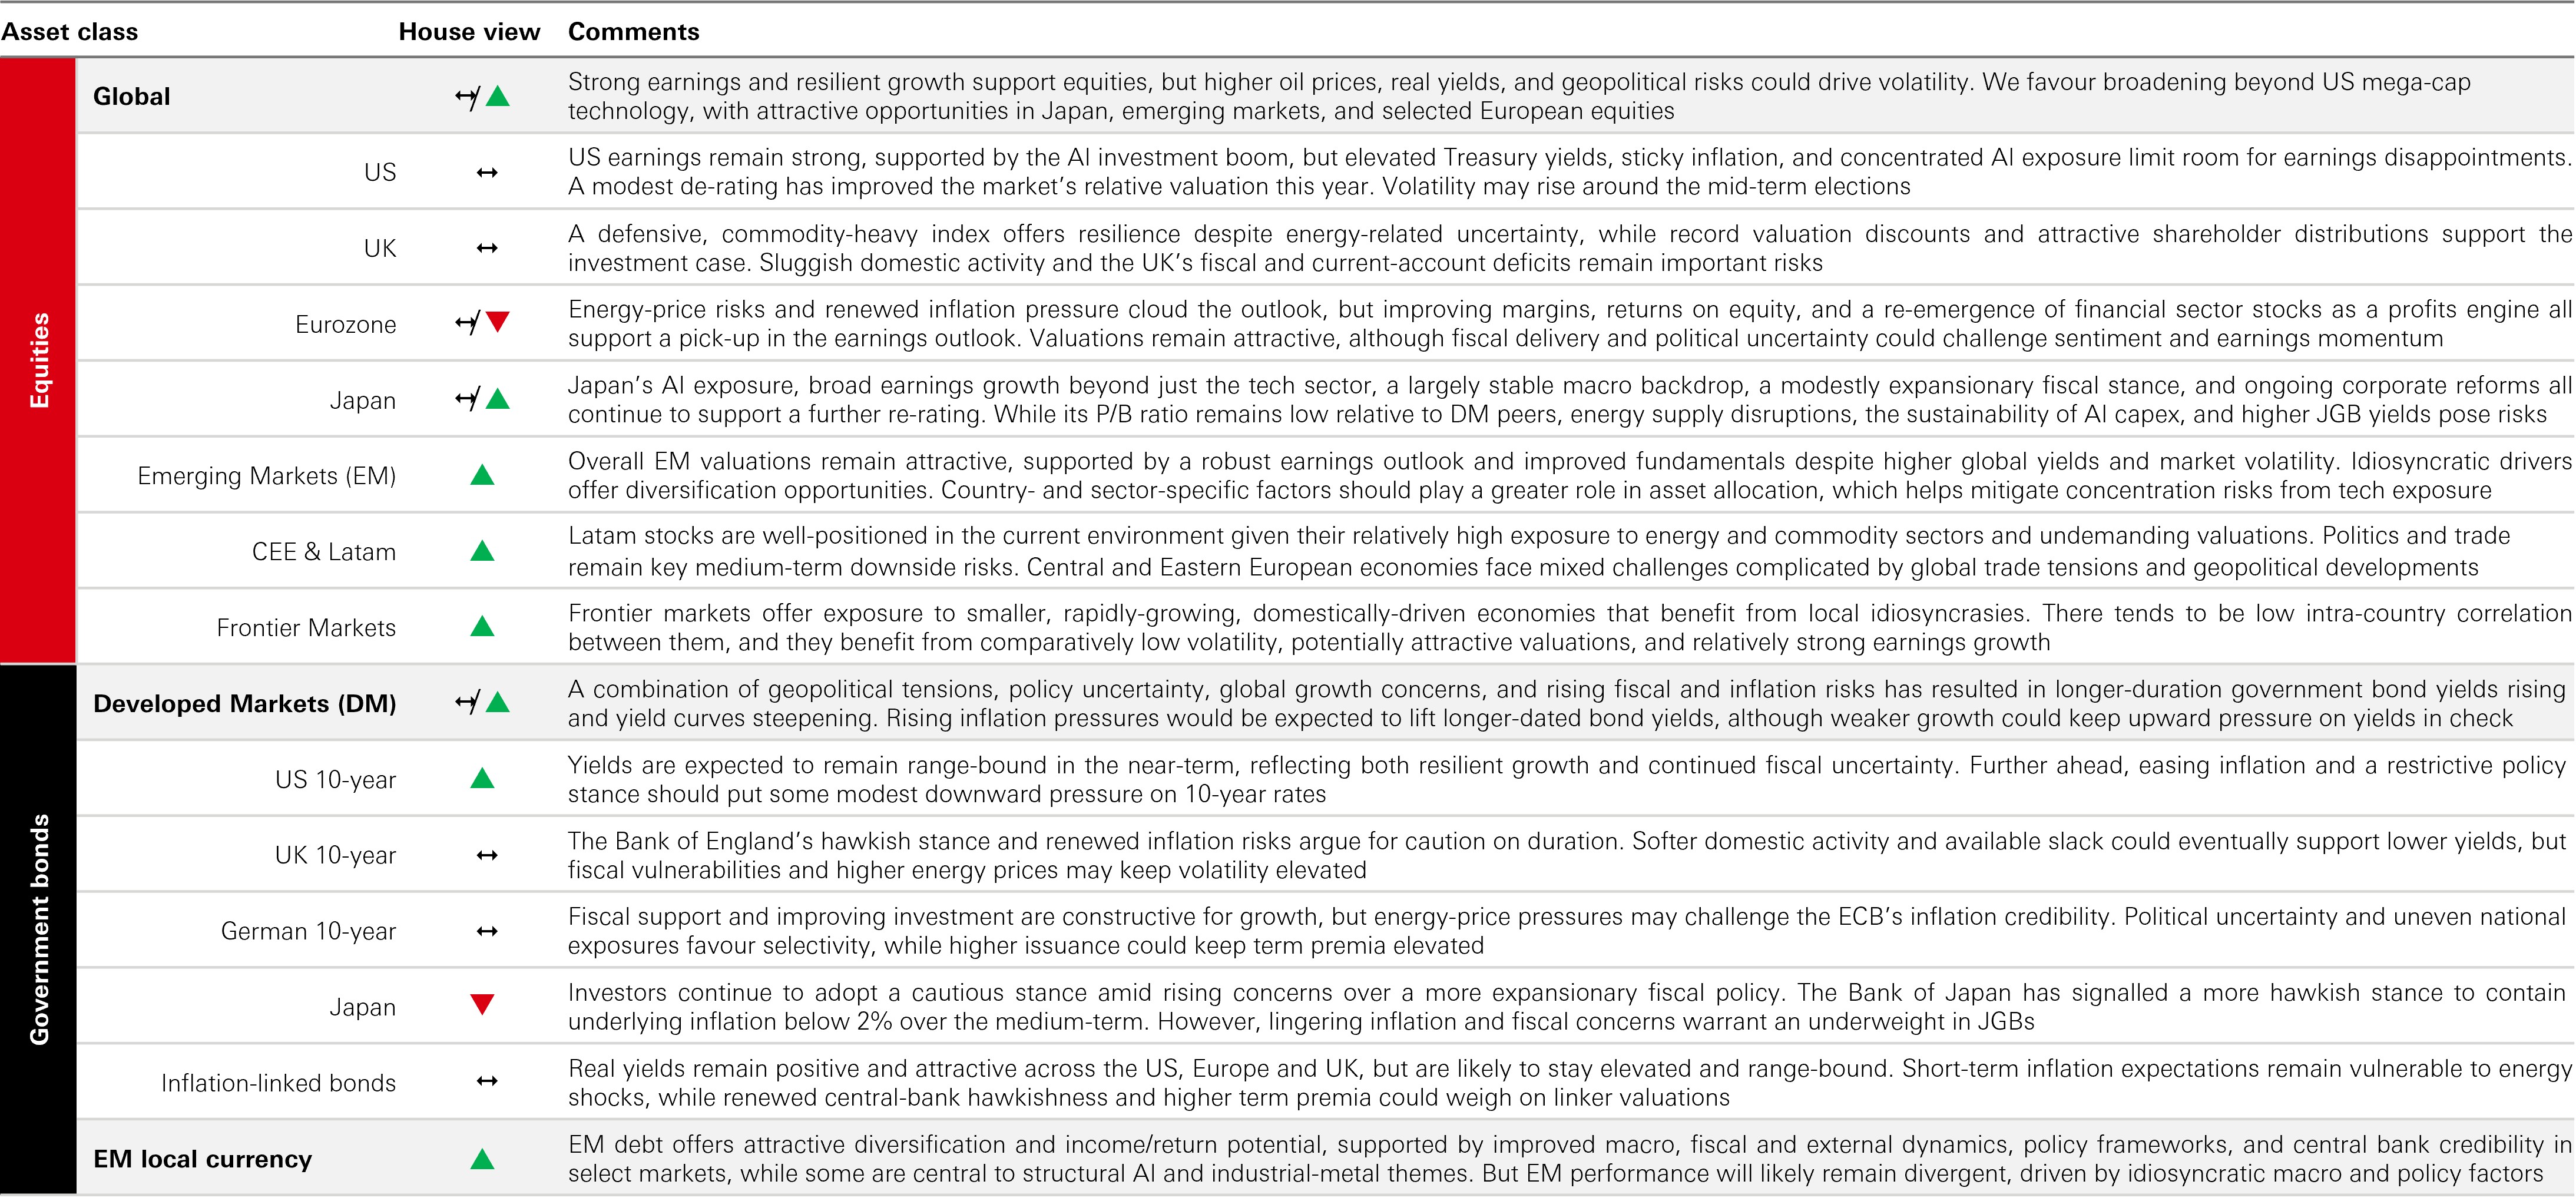
Click image to enlarge
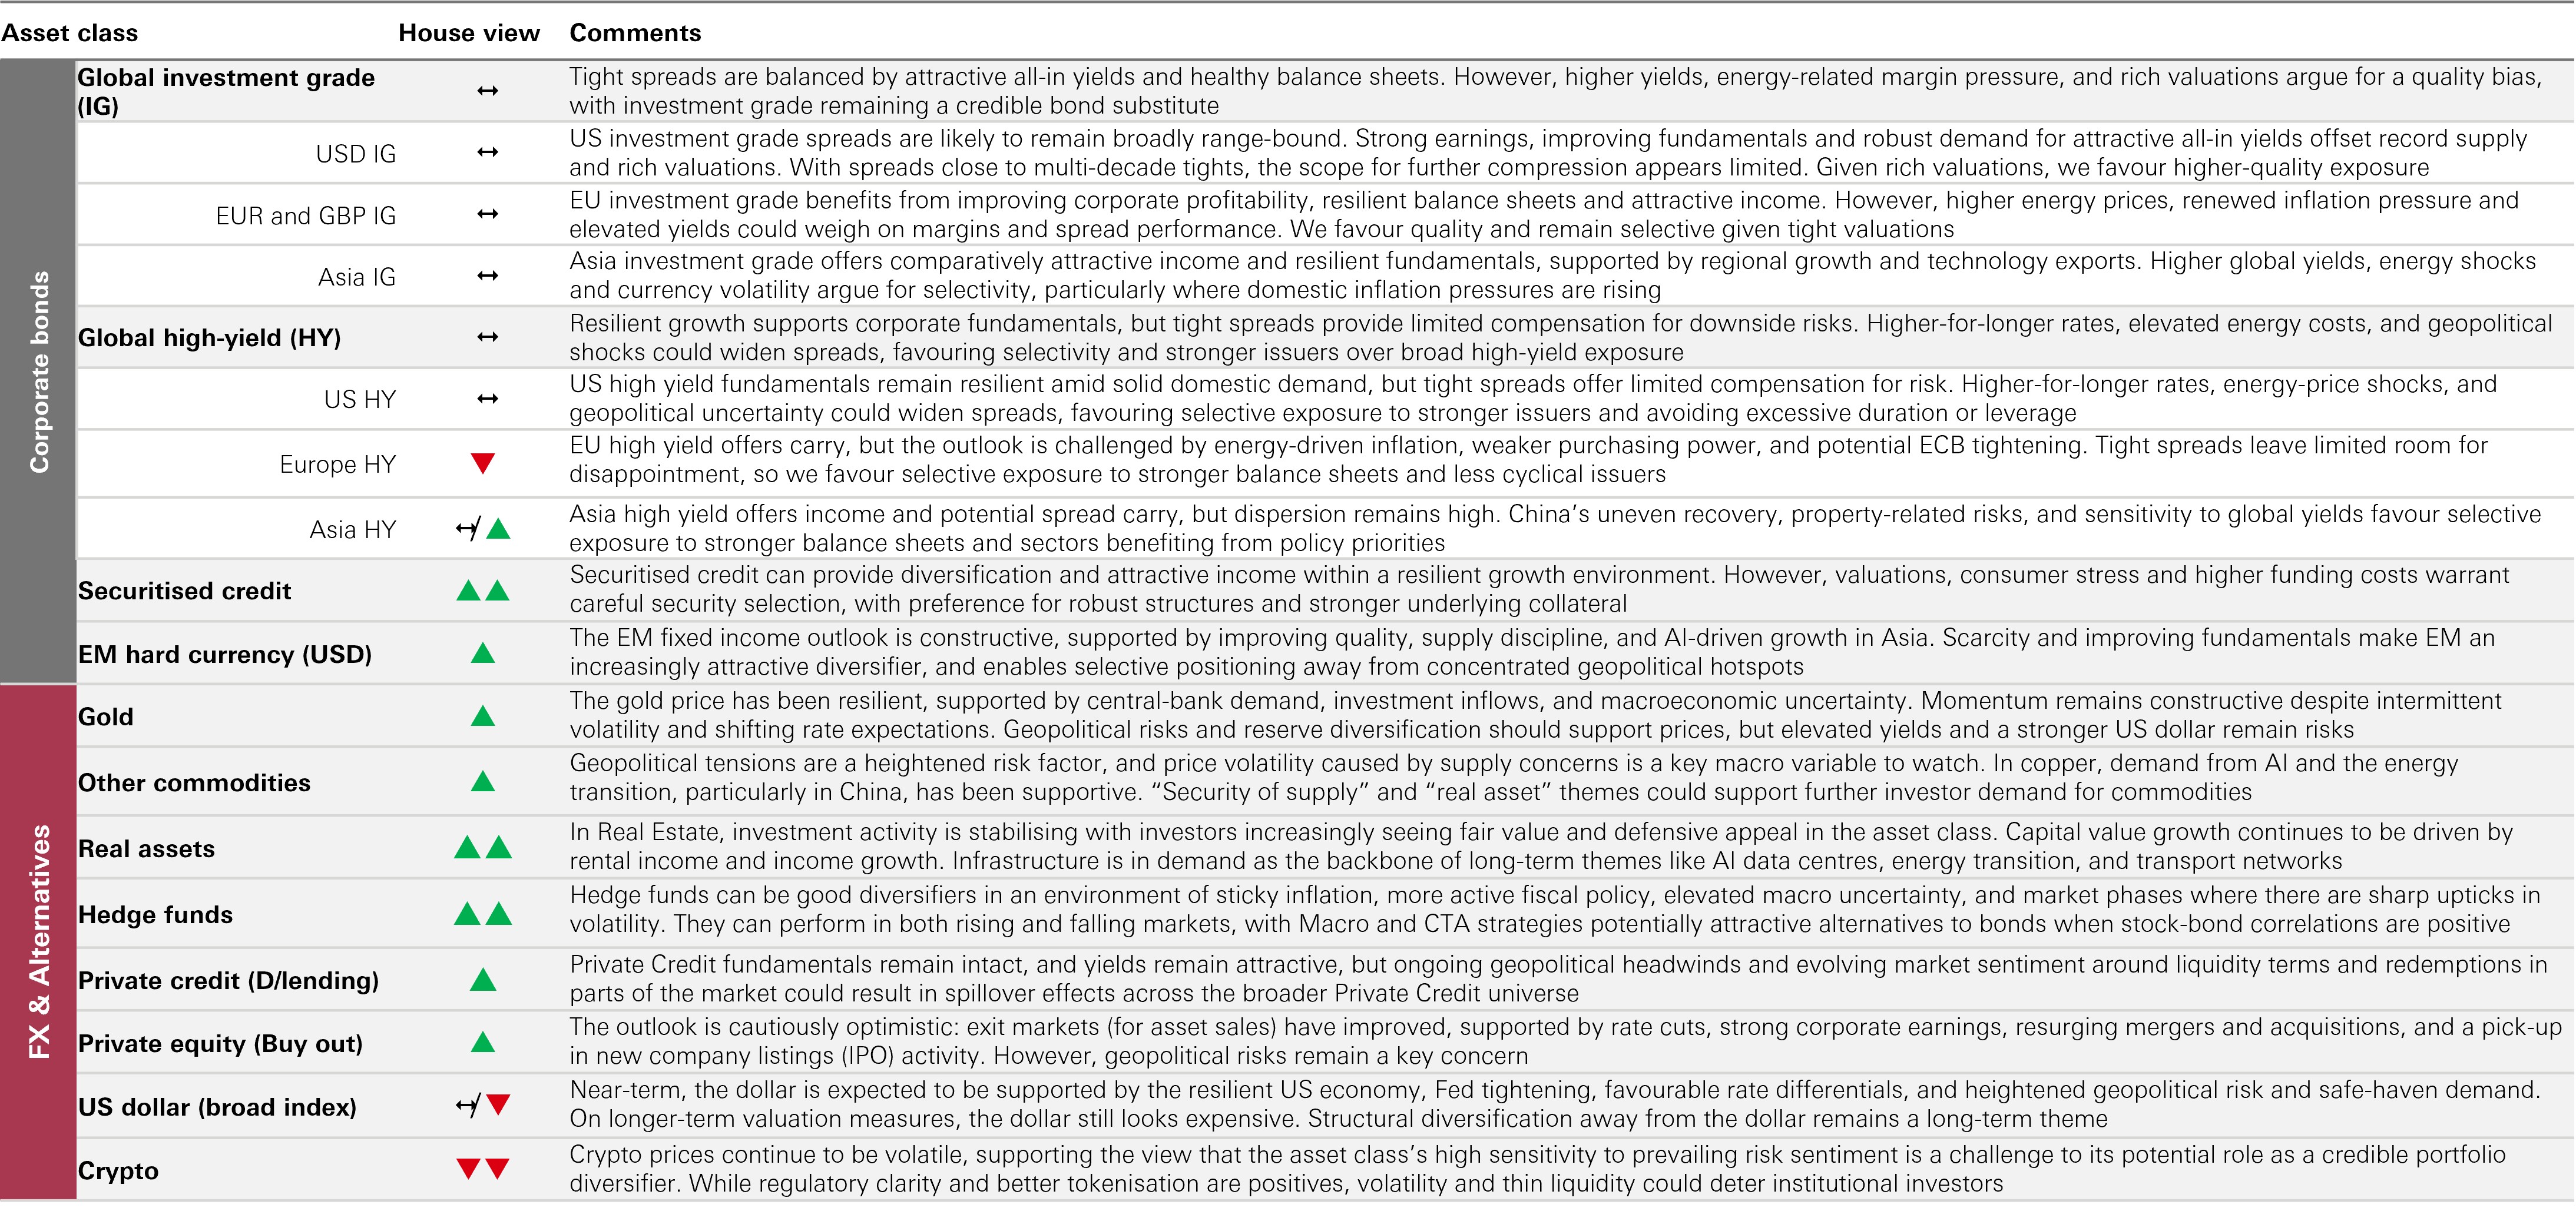
Click image to enlarge
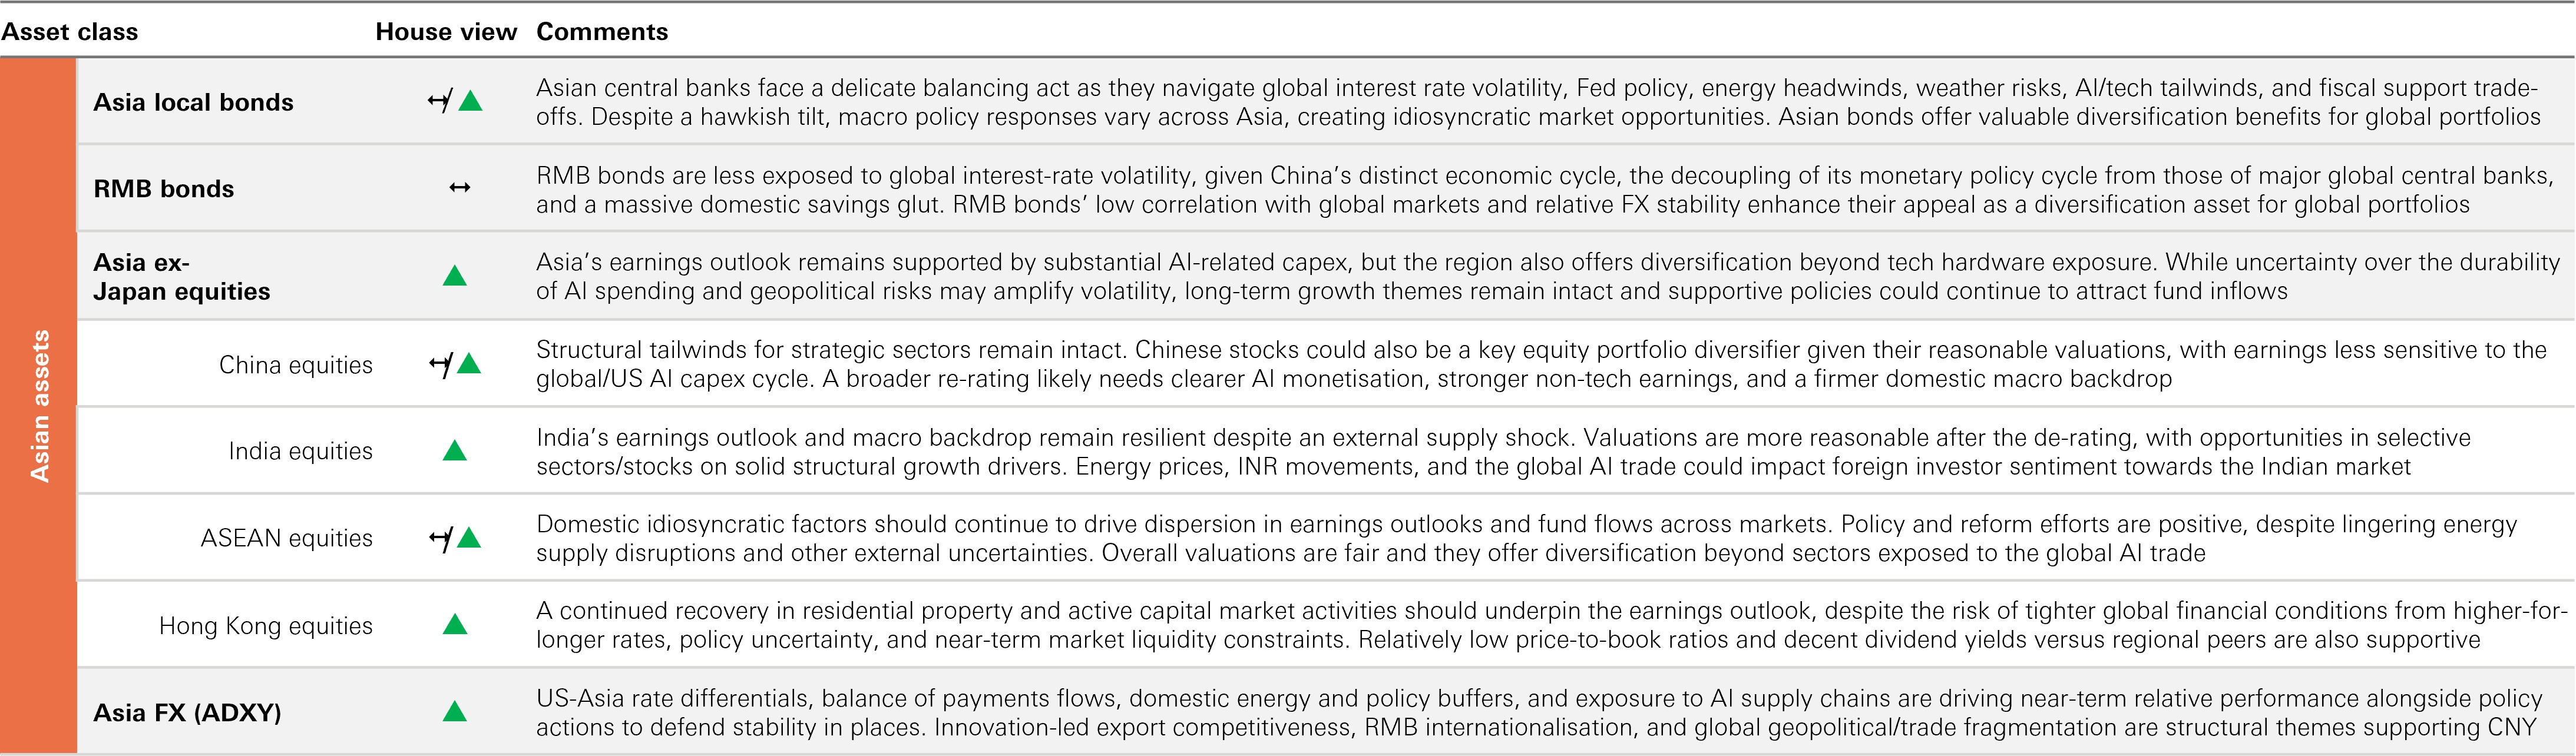
Click image to enlarge
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. Diversification does not ensure a profit or protect against loss. The views expressed above were held at the time of preparation and are subject to change without notice. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management as at October 2026.
On Top of Investors’ Minds
Will stocks crack under the weight of higher bond yields?
G7 bond yields have continued to increase in September. The rationale for the move higher probably reflects a combination of lingering fiscal concerns, stronger growth and sticky inflation, and indigestion coming from government and AI hyperscaler issuance.
For investors, a higher-for-longer regime could offer an opportunity to generate income from G7 bonds. But another key consideration is whether higher yields will break the stock market, along with other riskier asset classes. The 10-year yield at 5 per cent has been widely touted as a key tipping point.
The good news right now is the positive impact of the AI boom, that offsets other headwinds and buoys investor confidence and equity multiples. There will likely need to be a more decisive swing in investor enthusiasm around AI for there to be a major problem.
It will also be important to monitor the reaction of government to higher yields. At some point there could be pressure to cut deficits to keep debt trajectories under control. But a return to 2010s levels of austerity remains highly unlikely.
But crucially we know that if inflation is anchored at 2–3 per cent, central banks would retain the flexibility to adopt a dovish stance in periods of significant macro or market stress.
US 10-year yields and breakeven inflation, per cent
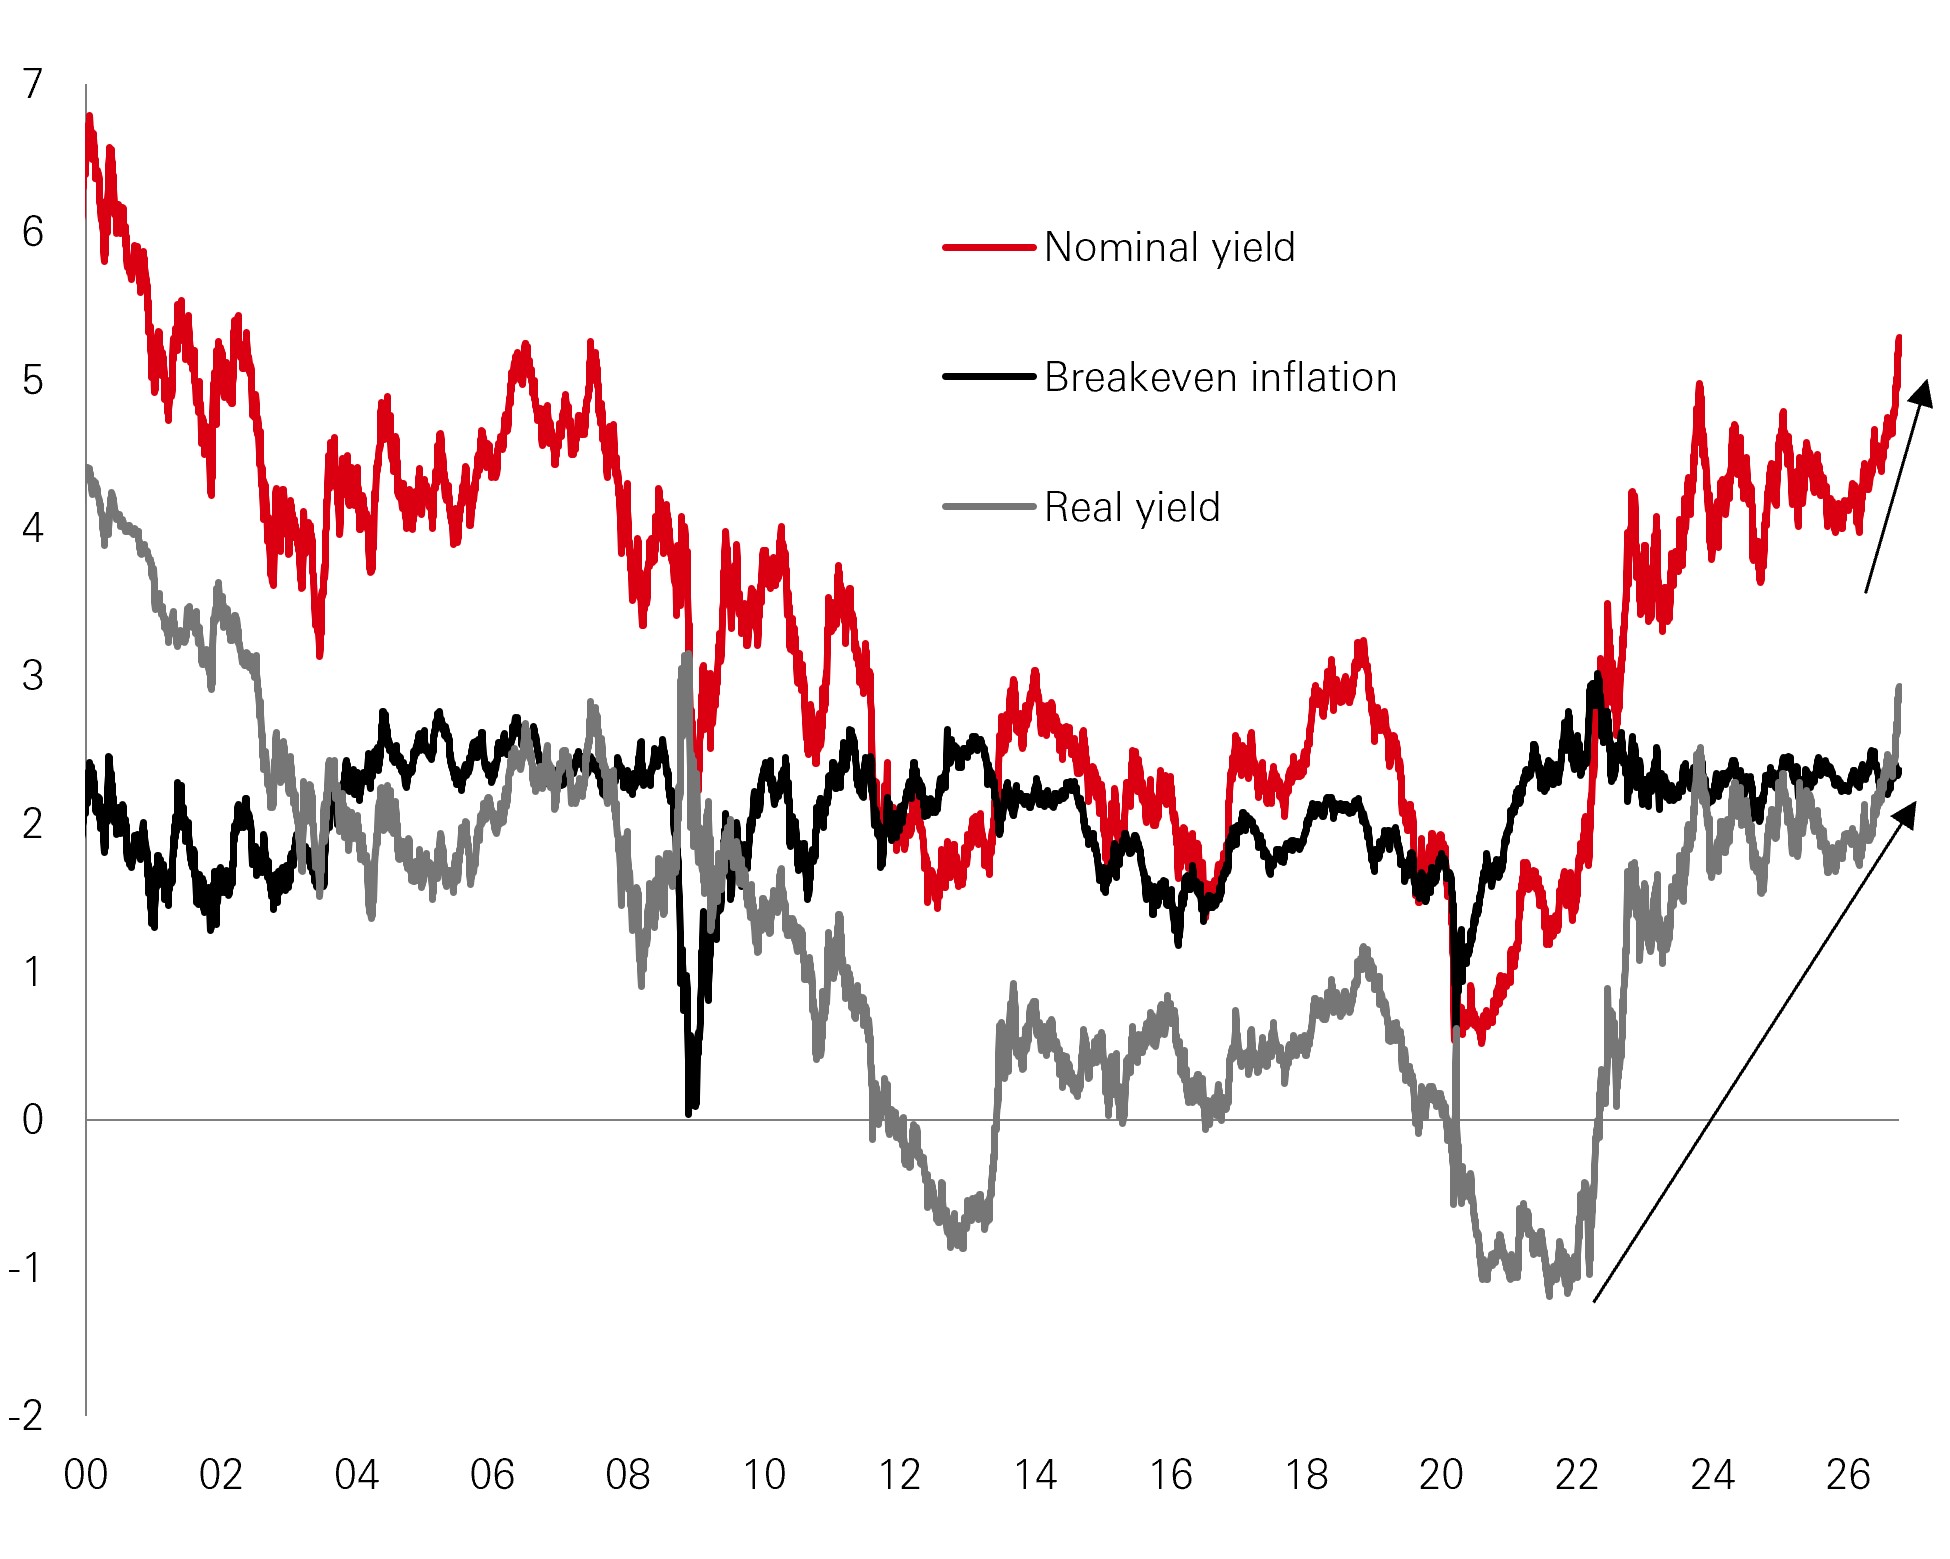
Click image to enlarge
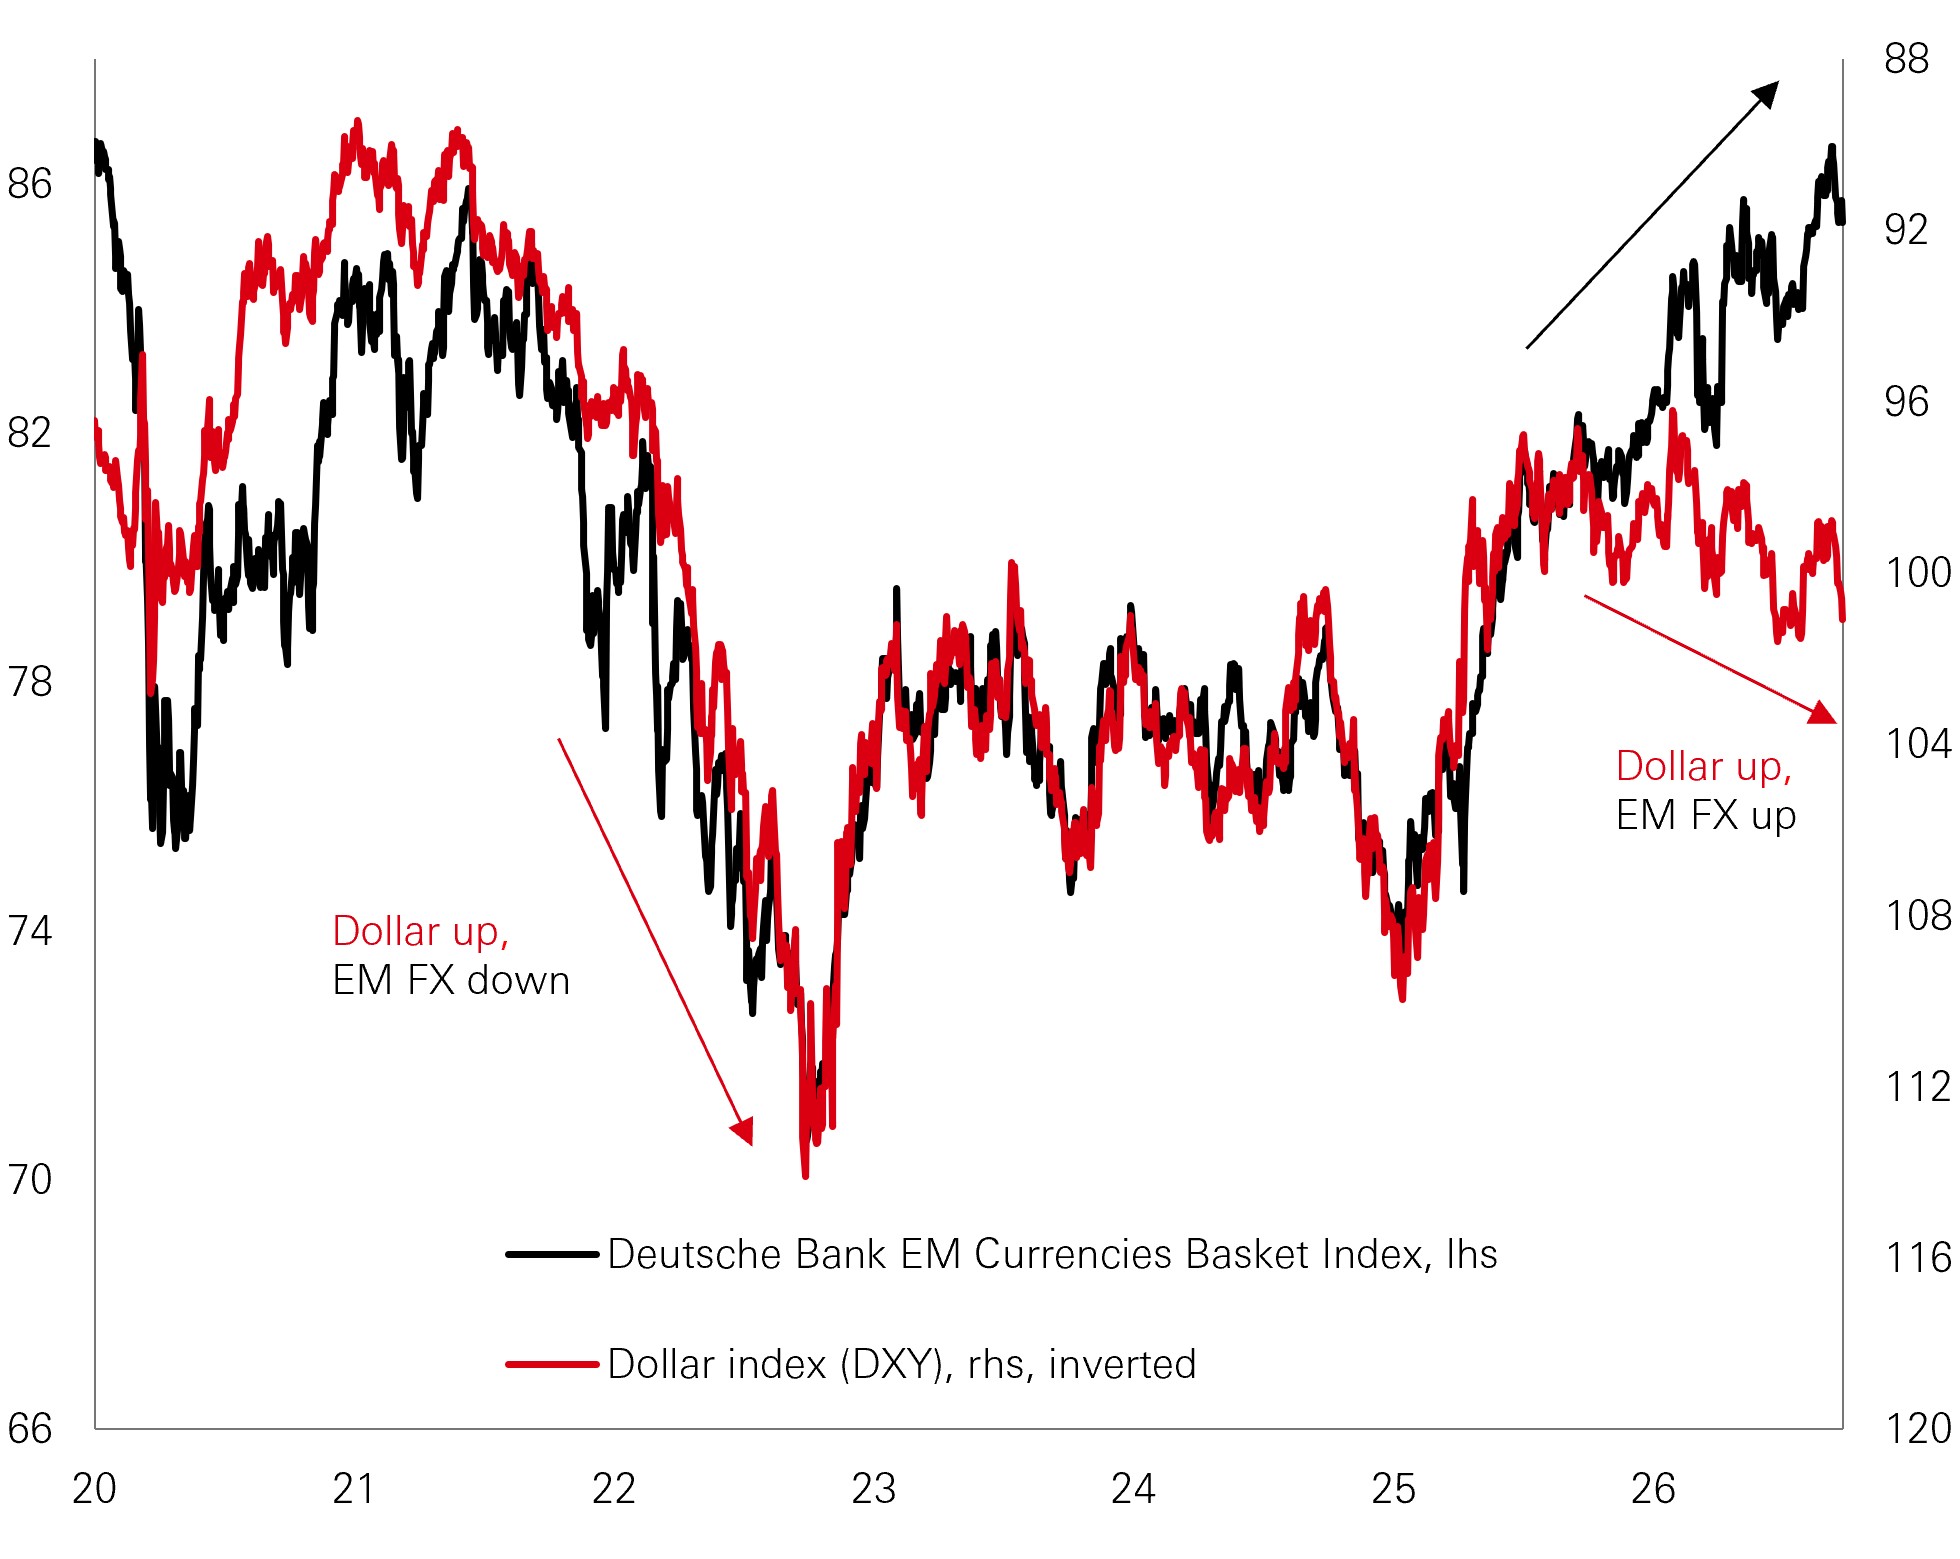
Could recent US dollar strength persist and how vulnerable is EM?
The US dollar has strengthened recently, supported by higher Treasury yields and rising oil prices. A hawkish 25bp Federal Reserve hike reinforced expectations of higher-for-longer interest rates, lifting both US yields and the dollar.
There are a few reasons to suggest why dollar strength may not persist. Other major central banks also face renewed inflation pressures, potentially limiting the US interest-rate advantage. Moreover, the relationship between the dollar and relative interest rates has been unstable in recent years and higher yields alone may not be enough to boost the currency. We also know that the dollar is still expensive on longer-term valuation measures.
But even if the dollar were to strengthen further, this may not be as bad for the EM complex as it has traditionally been. This year EM currencies have gained despite a strong dollar. This likely reflects the effects of better and more orthodox policymaking, the development of macro “fortresses”, and wide real yield cushions established by early rate hikes.
With EM currencies trading at historically cheap valuations and increasingly detached from Western cycles, we think there are opportunities for EM currency exposure to provide a durable, independent source of total return in global portfolios.
US dollar and EM FX indices
Click image to enlarge
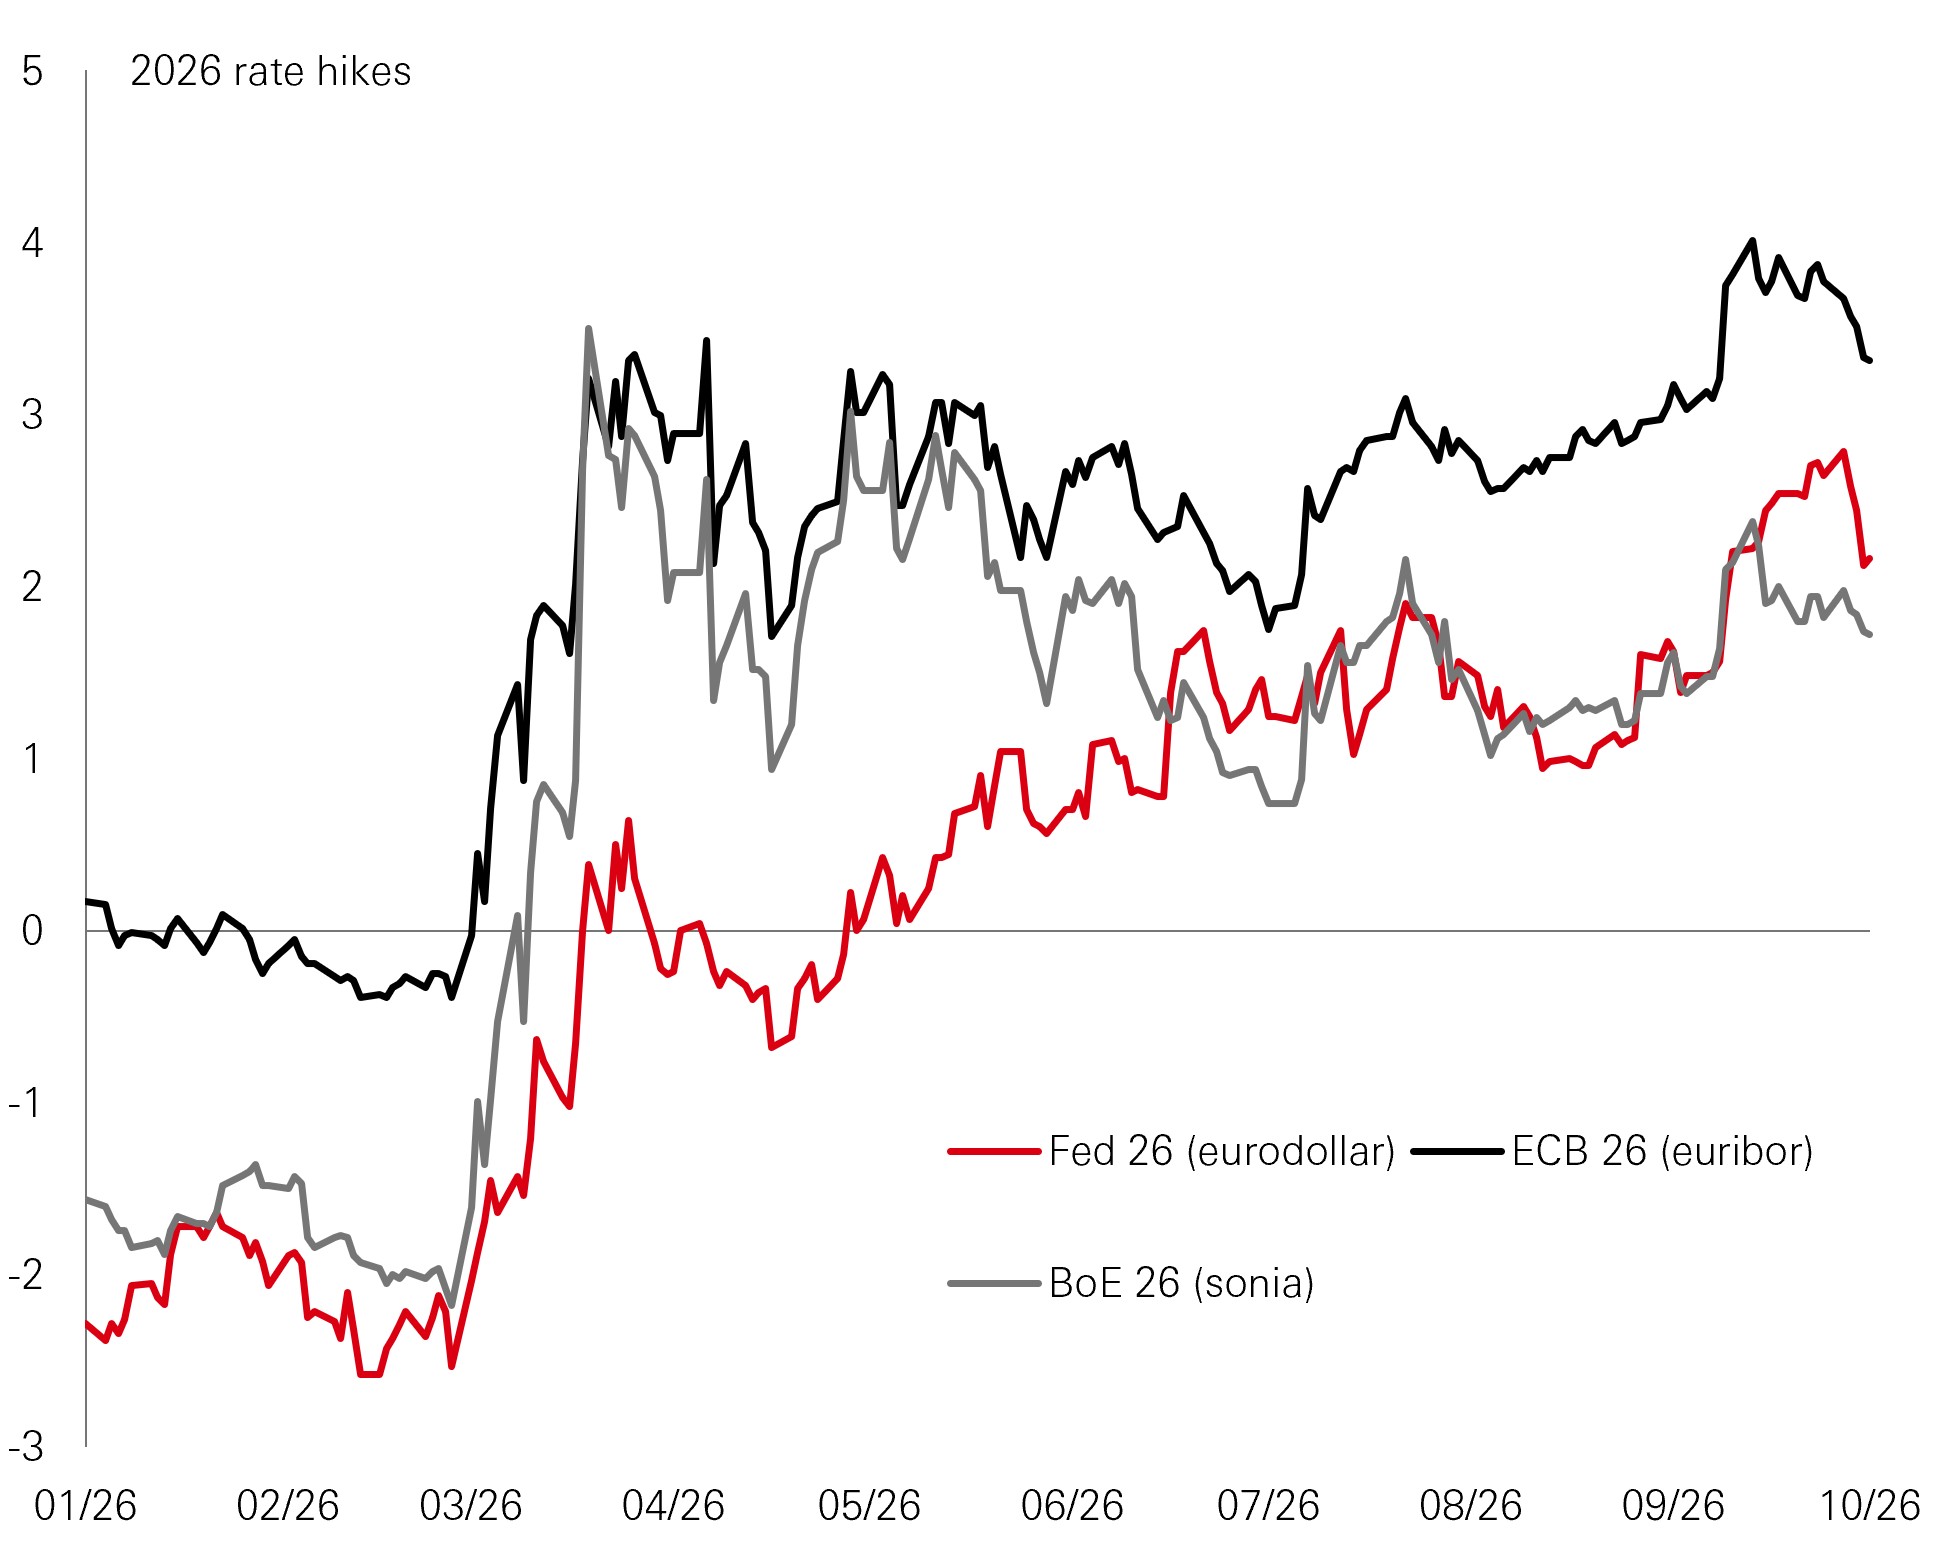
Will Western central banks deliver the hikes markets expect?
It’s been clear from recent Fed communications and September's rate hike that ignoring persistently above-target inflation is no longer an option. Amid higher oil prices, markets have responded by pricing in a significant degree of tightening: another Fed hike this year and two more in 2027.
However, the unbalanced nature of growth, combined with potential for supply-driven inflation to squeeze real incomes and profits of weaker consumers and businesses, means policy tightening could have unintended negative consequences.
Therefore, another one or two rate hikes appears to be a sensible middle ground that allows the Fed to manage upside inflation risks while limiting the chances of precipitating a downturn. It is also worth keeping in mind that core PCE, the Fed’s preferred measure of underlying inflation may be overstating inflation – other measures are closer to the Fed’s 2 per cent target.
For the Bank of England and European Central Bank (ECB), the outlook is more challenging. Their sensitivity to oil prices has also resulted in a significant degree of tightening being priced in. But much weaker growth, strained public finances and the possibility that energy prices normalise implies a higher chance that less tightening is actually delivered.
How many rate hikes from Fed, ECB, BoE in 2026?
Click image to enlarge
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Past performance does not predict future returns. Diversification does not ensure a profit or protect against loss. You cannot invest directly in an index. The level of yield is not guaranteed and may rise or fall in the future. Source: HSBC Asset Management as at October 2026.
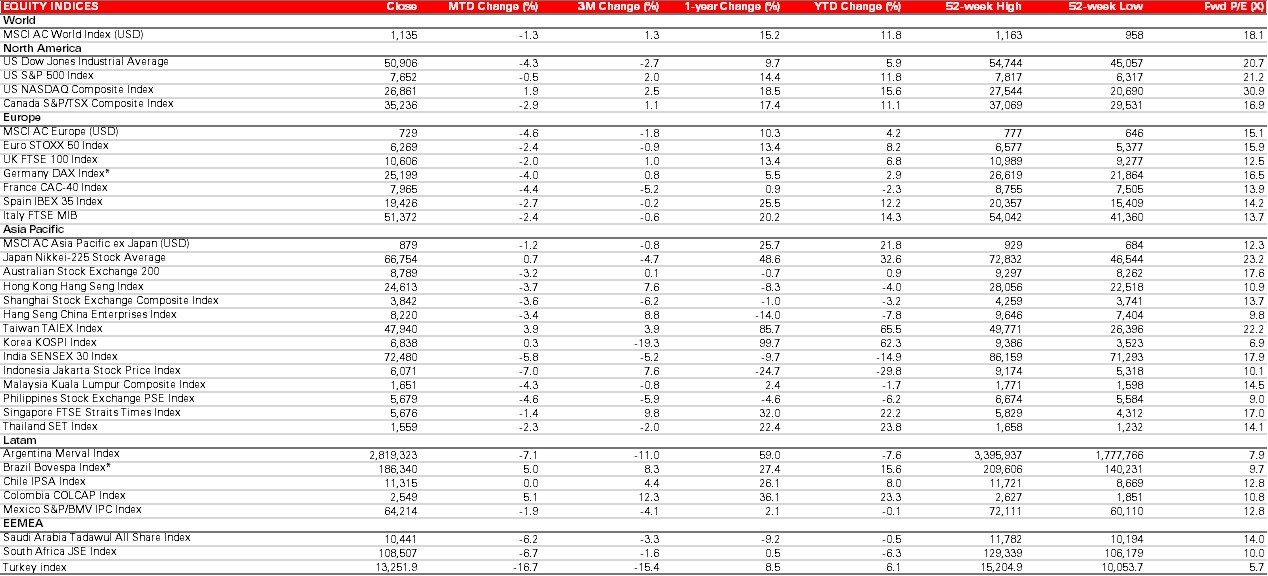
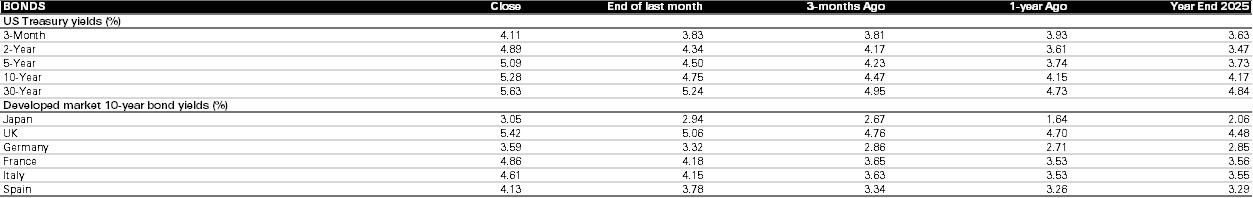
Market Data
September 2026
Click image to enlarge
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index.
Sources: Bloomberg, HSBC Asset Management. Data as at close of business 30 September 2026. (*) Indices expressed as total returns. All others are price returns.

Click image to enlarge
All total returns quoted in USD terms.
Data sourced from MSCI AC World Total Return Index, MSCI USA Total Return Index, MSCI AC Europe Total Return Index, MSCI AC Asia Pacific ex Japan Total Return Index, MSCI Japan Total Return Index, MSCI Latam Total Return Index and MSCI Emerging Markets Total Return Index.
Click image to enlarge
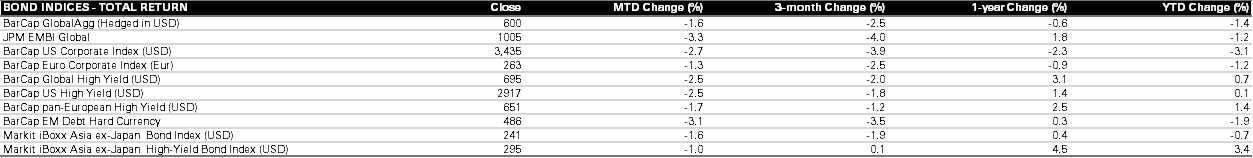
Click image to enlarge
Total return includes income from dividends and interest as well as appreciation or depreciation in the price of an asset over the given period. Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. This information shouldn’t be considered as a recommendation to invest in the country or sector shown. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Sources: Bloomberg, HSBC Asset Management. Data as at close of business 30 September 2026.
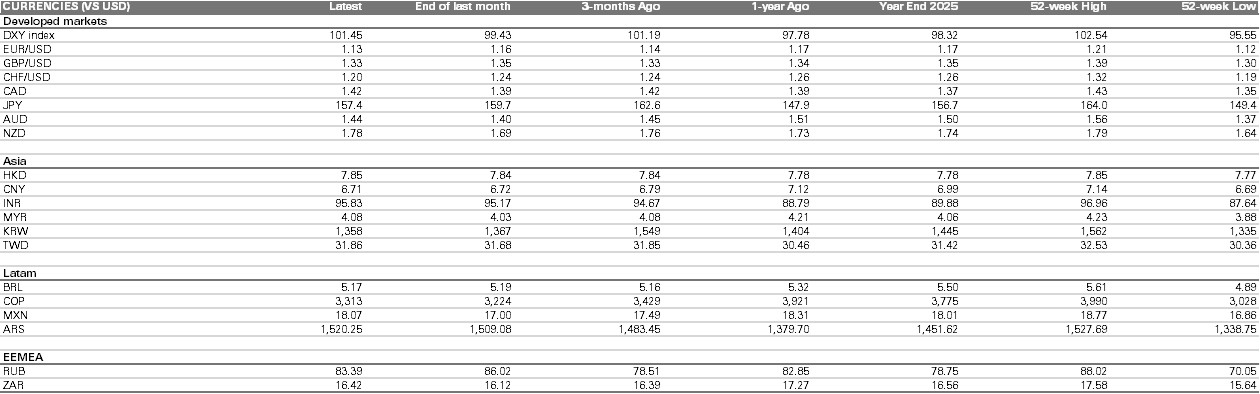
Click image to enlarge

Click image to enlarge
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. This information shouldn’t be considered as a recommendation to invest in the country or sector shown. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Sources: Bloomberg, HSBC Asset Management. Data as at close of business 30 September 2026.
Important Information
Basis of Views and Definitions of ‘Asset class positioning’ tables
- Views are based on regional HSBC Asset Management Asset Allocation meetings held throughout September 2026, HSBC Asset Management’s long-term expected return forecasts which were generated as at 31 August 2026, our portfolio optimisation process and actual portfolio positions.
- Icons: ⭡ View on this asset class has been upgraded – No change 🠗 View on this asset class has been downgraded.
- Underweight, overweight and neutral classifications are the high-level asset allocations tilts applied in diversified, typically multi-asset portfolios, which reflect a combination of our long-term valuation signals, our shorter-term cyclical views and actual positioning in portfolios. The views are expressed with reference to global portfolios. However, individual portfolio positions may vary according to mandate, benchmark, risk profile and the availability and riskiness of individual asset classes in different regions.
- “Overweight” implies that, within the context of a well-diversified typically multi-asset portfolio, and relative to relevant internal or external benchmarks, HSBC Global Asset Management has (or would have) a positive tilt towards the asset class.
- “Underweight” implies that, within the context of a well-diversified typically multi-asset portfolio, and relative to relevant internal or external benchmarks, HSBC Global Asset Management has (or would) have a negative tilt towards the asset class.
- “Neutral” implies that, within the context of a well-diversified typically multi-asset portfolio, and relative to relevant internal or external benchmarks HSBC Global Asset Management has (or would have) neither a particularly negative or positive tilt towards the asset class.
- For global investment-grade corporate bonds, the underweight, overweight and neutral categories for the asset class at the aggregate level are also based on high-level asset allocation considerations applied in diversified, typically multi-asset portfolios. However, USD investment-grade corporate bonds and EUR and GBP investment-grade corporate bonds are determined relative to the global investment-grade corporate bond universe.
- For Asia ex Japan equities, the underweight, overweight and neutral categories for the region at the aggregate level are also based on high-level asset allocation considerations applied in diversified, typically multi-asset portfolios. However, individual country views are determined relative to the Asia ex Japan equities universe as of 31 August 2026.
- Similarly, for EM government bonds, the underweight, overweight and neutral categories for the asset class at the aggregate level are also based on high-level asset allocation considerations applied in diversified, typically multi-asset portfolios. However, EM Asian Fixed income views are determined relative to the EM government bonds (hard currency) universe as of 30 September 2026.
Important information
For Professional Clients and intermediaries within countries and territories set out below; and for Institutional Investors and Financial Advisors in the US. This document should not be distributed to or relied upon by Retail clients/investors.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. The performance figures contained in this document relate to past performance, which should not be seen as an indication of future returns. Future returns will depend, inter alia, on market conditions, investment manager’s skill, risk level and fees. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries and territories with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries and territories in which they trade.
The contents of this document may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. All non-authorised reproduction or use of this document will be the responsibility of the user and may lead to legal proceedings. The material contained in this document is for general information purposes only and does not constitute advice or a recommendation to buy or sell investments. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. We do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed herein are those of HSBC Asset Management at the time of preparation and are subject to change at any time. These views may not necessarily indicate current portfolios' composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients' objectives, risk preferences, time horizon, and market liquidity. Foreign and emerging markets: investments in foreign markets involve risks such as currency rate fluctuations, potential differences in accounting and taxation policies, as well as possible political, economic, and market risks. These risks are heightened for investments in emerging markets which are also subject to greater illiquidity and volatility than developed foreign markets. This commentary is for information purposes only. It is a marketing communication and does not constitute investment advice or a recommendation to any reader of this content to buy or sell investments nor should it be regarded as investment research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. This document is not contractually binding nor are we required to provide this to you by any legislative provision.
All data from HSBC Asset Management unless otherwise specified. Any third-party information has been obtained from sources we believe to be reliable, but which we have not independently verified.
HSBC Asset Management is the brand name for the asset management business of HSBC Group, which includes the investment activities that may be provided through our local regulated entities. HSBC Asset Management is a group of companies in many countries and territories throughout the world that are engaged in investment advisory and fund management activities, which are ultimately owned by HSBC Holdings Plc. (HSBC Group).
- In Australia, this document is issued by HSBC Bank Australia Limited ABN 48 006 434 162, AFSL 232595, for HSBC Global Asset Management (Hong Kong) Limited ARBN 132 834 149 and HSBC Global Asset Management (UK) Limited ARBN 633 929 718. This document is for institutional investors only and is not available for distribution to retail clients (as defined under the Corporations Act). HSBC Global Asset Management (Hong Kong) Limited and HSBC Global Asset Management (UK) Limited are exempt from the requirement to hold an Australian financial services license under the Corporations Act in respect of the financial services they provide. HSBC Global Asset Management (Hong Kong) Limited is regulated by the Securities and Futures Commission of Hong Kong under the Hong Kong laws, which differ from Australian laws. HSBC Global Asset Management (UK) Limited is regulated by the Financial Conduct Authority of the United Kingdom and, for the avoidance of doubt, includes the Financial Services Authority of the United Kingdom as it was previously known before 1 April 2013, under the laws of the United Kingdom, which differ from Australian laws;
- In Bermuda, this document is issued by HSBC Global Asset Management (Bermuda) Limited, of 37 Front Street, Hamilton, Bermuda which is licensed to conduct investment business by the Bermuda Monetary Authority;
- In France, Belgium, Netherlands, Luxembourg, Portugal, Greece, Finland, Norway, Denmark, Spain and Sweden this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026);
- In Germany, this document is issued by HSBC Global Asset Management (Deutschland) GmbH which is regulated by BaFin (German clients) respective by the Austrian Financial Market Supervision FMA (Austrian clients);
- In Hong Kong, this document is issued by HSBC Global Asset Management (Hong Kong) Limited, which is regulated by the Securities and Futures Commission. This content has not been reviewed by the Securities and Futures Commission;
- In India, this document is issued by HSBC Asset Management (India) Pvt Ltd. which is regulated by the Securities and Exchange Board of India;
- In Italy, this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026), through its Italian branch, regulated by Banca d’Italia and Commissione Nazionale per le Società e la Borsa (Consob);
- In Japan, this document is issued by HSBC Asset Management (Japan) Ltd (JRN 3010001124868), regulated by the Financial Services Agency;
- In Malta, this document is issued by HSBC Global Asset Management (Malta) Limited which is regulated and licensed to conduct Investment Services by the Malta Financial Services Authority under the Investment Services Act;
- In Mexico, this document is issued by HSBC Global Asset Management (Mexico), SA de CV, Sociedad Operadora de Fondos de Inversión, Grupo Financiero HSBC which is regulated by Comisión Nacional Bancaria y de Valores;
- In the United Arab Emirates, this document is issued by HSBC Investment Funds (Luxembourg) S.A. – Dubai Branch (Level 20, HSBC Tower, PO Box 66, Downtown Dubai, United Arab Emirates) regulated by the Capital Market Authority (CMA) in the UAE to conduct investment fund management, portfolios management, fund administration activities (CMA Category 2 license No.20200000336) and promotion activities (CMA Category 5 license No.20200000327).
- In the United Arab Emirates, this document is issued by HSBC Global Asset Management MENA, a unit within HSBC Bank Middle East Limited, U.A.E Branch, PO Box 66 Dubai, UAE, regulated by the Central Bank of the U.A.E. and the Capital Market Authority in the UAE under CMA license number 602004 for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority. HSBC Bank Middle East Limited is a member of the HSBC Group and HSBC Global Asset Management MENA are marketing the relevant product only in a sub-distributing capacity on a principal-to-principal basis. HSBC Global Asset Management MENA may not be licensed under the laws of the recipient’s country of residence and therefore may not be subject to supervision of the local regulator in the recipient’s country of residence. One of more of the products and services of the manufacturer may not have been approved by or registered with the local regulator and the assets may be booked outside of the recipient’s country of residence.
- In Singapore, this document is issued by HSBC Global Asset Management (Singapore) Limited, which is regulated by the Monetary Authority of Singapore. The content in the document/video has not been reviewed by the Monetary Authority of Singapore;
- In Switzerland, this document is issued by HSBC Global Asset Management (Switzerland) AG. This document is intended for professional investor use only. For opting in and opting out according to FinSA, please refer to our website; if you wish to change your client categorization, please inform us. HSBC Global Asset Management (Switzerland) AG having its registered office at Gartenstrasse 26, PO Box, CH-8002 Zurich has a licence as an asset manager of collective investment schemes and as a representative of foreign collective investment schemes. Disputes regarding legal claims between the Client and HSBC Global Asset Management (Switzerland) AG can be settled by an ombudsman in mediation proceedings. HSBC Global Asset Management (Switzerland) AG is affiliated to the ombudsman FINOS having its registered address at Talstrasse 20, 8001 Zurich. There are general risks associated with financial instruments, please refer to the Swiss Banking Association (“SBA”) Brochure “Risks Involved in Trading in Financial Instruments”;
- In Taiwan, this document is issued by HSBC Global Asset Management (Taiwan) Limited which is regulated by the Financial Supervisory Commission R.O.C. (Taiwan);
- In Turkiye, this document is issued by HSBC Asset Management A.S. Turkiye (AMTU) which is regulated by Capital Markets Board of Turkiye. Any information here is not intended to distribute in any jurisdiction where AMTU does not have a right to. Any views here should not be perceived as investment advice, product/service offer and/or promise of income. Information given here might not be suitable for all investors and investors should be giving their own independent decisions. The investment information, comments and advice given herein are not part of investment advice activity. Investment advice services are provided by authorized institutions to persons and entities privately by considering their risk and return preferences, whereas the comments and advice included herein are of a general nature. Therefore, they may not fit your financial situation and risk and return preferences. For this reason, making an investment decision only by relying on the information given herein may not give rise to results that fit your expectations.
- In the UK, this document is issued by HSBC Global Asset Management (UK) Limited, which is authorised and regulated by the Financial Conduct Authority;
- In the US, this document is issued by HSBC Securities (USA) Inc., an HSBC broker dealer registered in the US with the Securities and Exchange Commission under the Securities Exchange Act of 1934. HSBC Securities (USA) Inc. is also a member of NYSE/FINRA/SIPC. HSBC Securities (USA) Inc. is not authorized by or registered with any other non-US regulatory authority. The contents of this document are confidential and may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose without prior written permission.
- In Chile, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Chilean inspections or regulations and are not covered by warranty of the Chilean state. Obtain information about the state guarantee to deposits at your bank or on www.cmfchile.cl;
- In Colombia, HSBC Bank USA NA has an authorized representative by the Superintendencia Financiera de Colombia (SFC) whereby its activities conform to the General Legal Financial System. SFC has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Colombia and is not for public distribution;
- In Costa Rica, the Fund and any other products or services referenced in this document are not registered with the Superintendencia General de Valores (“SUGEVAL”) and no regulator or government authority has reviewed this document, or the merits of the products and services referenced herein. This document is directed at and intended for institutional investors only.
- In Peru, HSBC Bank USA NA has an authorized representative by the Superintendencia de Banca y Seguros in Perú whereby its activities conform to the General Legal Financial System - Law No. 26702. Funds have not been registered before the Superintendencia del Mercado de Valores (SMV) and are being placed by means of a private offer. SMV has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Perú and is not for public distribution;
- In Uruguay, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Uruguayan inspections or regulations and are not covered by warranty of the Uruguayan state. Further information may be obtained about the state guarantee to deposits at your bank or on www.bcu.gub.uy.
Copyright © HSBC Global Asset Management Limited 2026. All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of HSBC Asset Management.
Content ID: D077718_V1.0; Expiry Date: 01.09.2027